Blog

Karim Naoum on AI in Real Estate Investing: What Helps and What’s Hype

Every few months a new tool promises to find deals while you sleep, screen tenants in seconds, and run your rentals on autopilot. That’s the pitch for AI in real estate investing. Some of it is useful. A lot of it is a demo.

Rental real estate is a slow, local, paperwork-heavy business. That makes it a good test for AI in real estate investing: the technology is strong at reading, sorting, and drafting, and weak at the things that decide whether a rental succeeds, like the condition of a furnace or the character of a block.

Karim Naoum’s approach to investing is built on simple numbers and long holding periods. As of 2026 his portfolio includes 400+ properties, counting wholly owned properties and partnership interests, most of them rented to families with Housing Choice Vouchers. From that operator’s view, the question about any tool is plain: does it save time or improve a decision, without creating a new risk? This article sorts AI uses into what helps today, what falls short, and where the legal risks sit.

Where AI in real estate investing helps today

The best current uses share a pattern. They take a task that’s repetitive, text-heavy, and easy to check, and they make it faster.

  • Summarizing documents. Leases, inspection reports, insurance policies, and HOA rules are long. An AI assistant can pull out dates, obligations, and unusual clauses in a minute. You still read the parts that matter.
  • Drafting routine messages. Maintenance updates, appointment reminders, and vendor requests. A draft you edit is faster than a blank page.
  • Organizing numbers. Turning a bank export into categorized expenses, or building a first version of a deal spreadsheet.
  • Research support. Explaining an unfamiliar term, outlining questions for a lender, or comparing two approaches.
  • Translation. Communicating clearly with tenants and vendors in the language they prefer.

None of this is glamorous. All of it frees up time for the work that can’t be delegated to software.

Deal screening and comps

This is where the marketing is loudest, so it’s worth being specific.

What works. AI is good at narrowing a long list. Give it your criteria, such as price range, bedroom count, and minimum rent, and it can sort listings, flag the ones that fit, and run a first-pass calculation on each. For an investor who looks at fifty properties to buy one, that’s real time saved.

What doesn’t. The inputs still have to be right, and the important ones can’t be guessed.

  • Rent. For a voucher tenant, rent depends on the local housing agency’s payment standard, the utility allowance, and a rent reasonableness comparison. An automated rent estimate doesn’t know those. You look up Fair Market Rents on HUD USER and call the agency.
  • Condition. Photos hide roofs, wiring, and plumbing. A model can’t smell a wet basement.
  • Location at street level. In many cities, one block rents easily and the next doesn’t. Averages by ZIP code miss that.
  • Value. Automated value estimates are least reliable where sales are few and homes vary widely, which describes many lower-priced rental neighborhoods.

A fair rule: let software build the shortlist, and let people verify everything on it. Karim’s investing principles start from numbers you can check, and that doesn’t change because a tool produced the first draft.
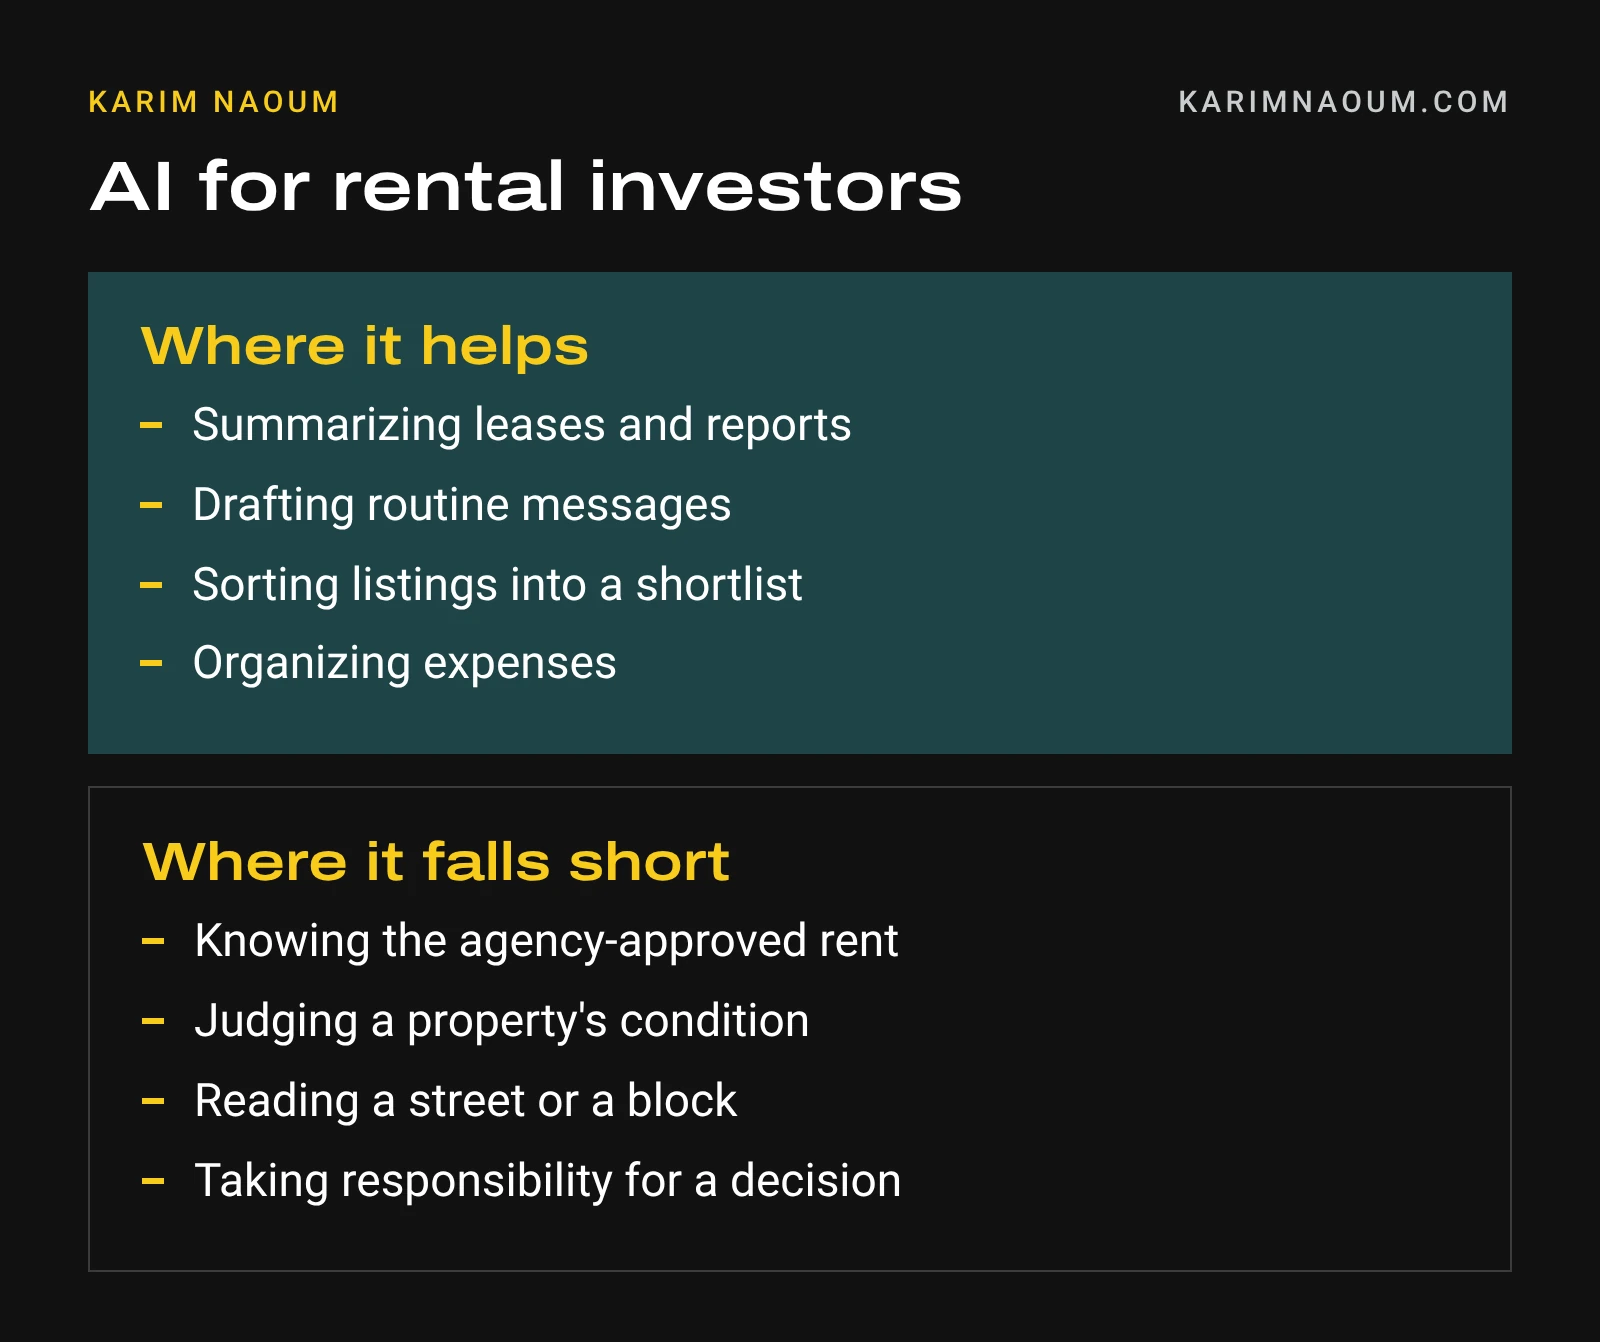
Where AI helps rental investors and where it falls short, comparing document summaries, drafts, and shortlists against rent, condition, and street-level judgment

Admin and tenant communication

For owners with more than a few units, administration is where hours go. AI can help with:

  • Maintenance intake. Sorting requests by urgency and collecting details before a person responds.
  • After-hours answers to common questions, such as how to submit a repair request or when rent is due.
  • Bookkeeping support. Categorizing transactions and flagging unusual ones.
  • Scheduling vendors and inspections.

The line to hold is this: software can handle logistics, but a person should handle anything that affects someone’s housing. A late rent conversation, a lease violation, a dispute about a repair. Those call for judgment, and often for patience. A tenant who can reach a human when it matters is more likely to stay, and long tenancies are what make rentals work. Karim’s piece on what every landlord should understand about voucher tenants makes the same point from the tenant’s side.

Where AI in real estate investing falls short

AI tools have three weaknesses that matter for investors.

They can be confidently wrong. Language models sometimes state false things in a fluent, certain tone. In real estate, the wrong figure for a payment standard or a made-up local rule can cost real money. Check anything that matters against the original source.

They don’t know your local rules. Landlord-tenant law, housing agency procedures, and licensing requirements vary by state, county, and city, and they change. General answers aren’t legal advice.

They can’t take responsibility. If an automated system makes a bad decision, the owner answers for it. That’s true of screening, pricing, and everything else.

There’s also a privacy point. Tenant applications contain Social Security numbers, income records, and other sensitive data. Don’t paste that into a tool unless you know how it stores and uses the information.

Fair housing risks of automation

This is the area where a careless shortcut can turn into a legal problem.

Tenant screening tools increasingly use algorithms to score or reject applicants. In 2024, HUD issued guidance on how the Fair Housing Act applies to tenant screening and to AI-driven advertising. The core message: using software doesn’t move responsibility off the housing provider. If a screening tool produces discriminatory outcomes, the owner who relied on it can be held accountable.

Practical steps that follow from that:

  • Know what your screening tool measures. Ask the vendor what data and criteria it uses.
  • Use written, consistent criteria that relate to being a good tenant, and apply them to everyone.
  • Don’t accept a score blindly. Look at the underlying record. Old, minor, or irrelevant items shouldn’t sink an applicant automatically.
  • Give applicants a chance to correct errors. Records contain mistakes.
  • Be careful with ad targeting. Showing a listing only to certain groups can itself be a fair housing problem.
  • Know your local law on vouchers. In many states and cities, rejecting an applicant because they use a voucher is illegal.

For voucher tenancies, the housing agency confirms program eligibility, but choosing the tenant is still the owner’s job. This guide to Section 8 tenant screening explains what owners can and can’t consider.
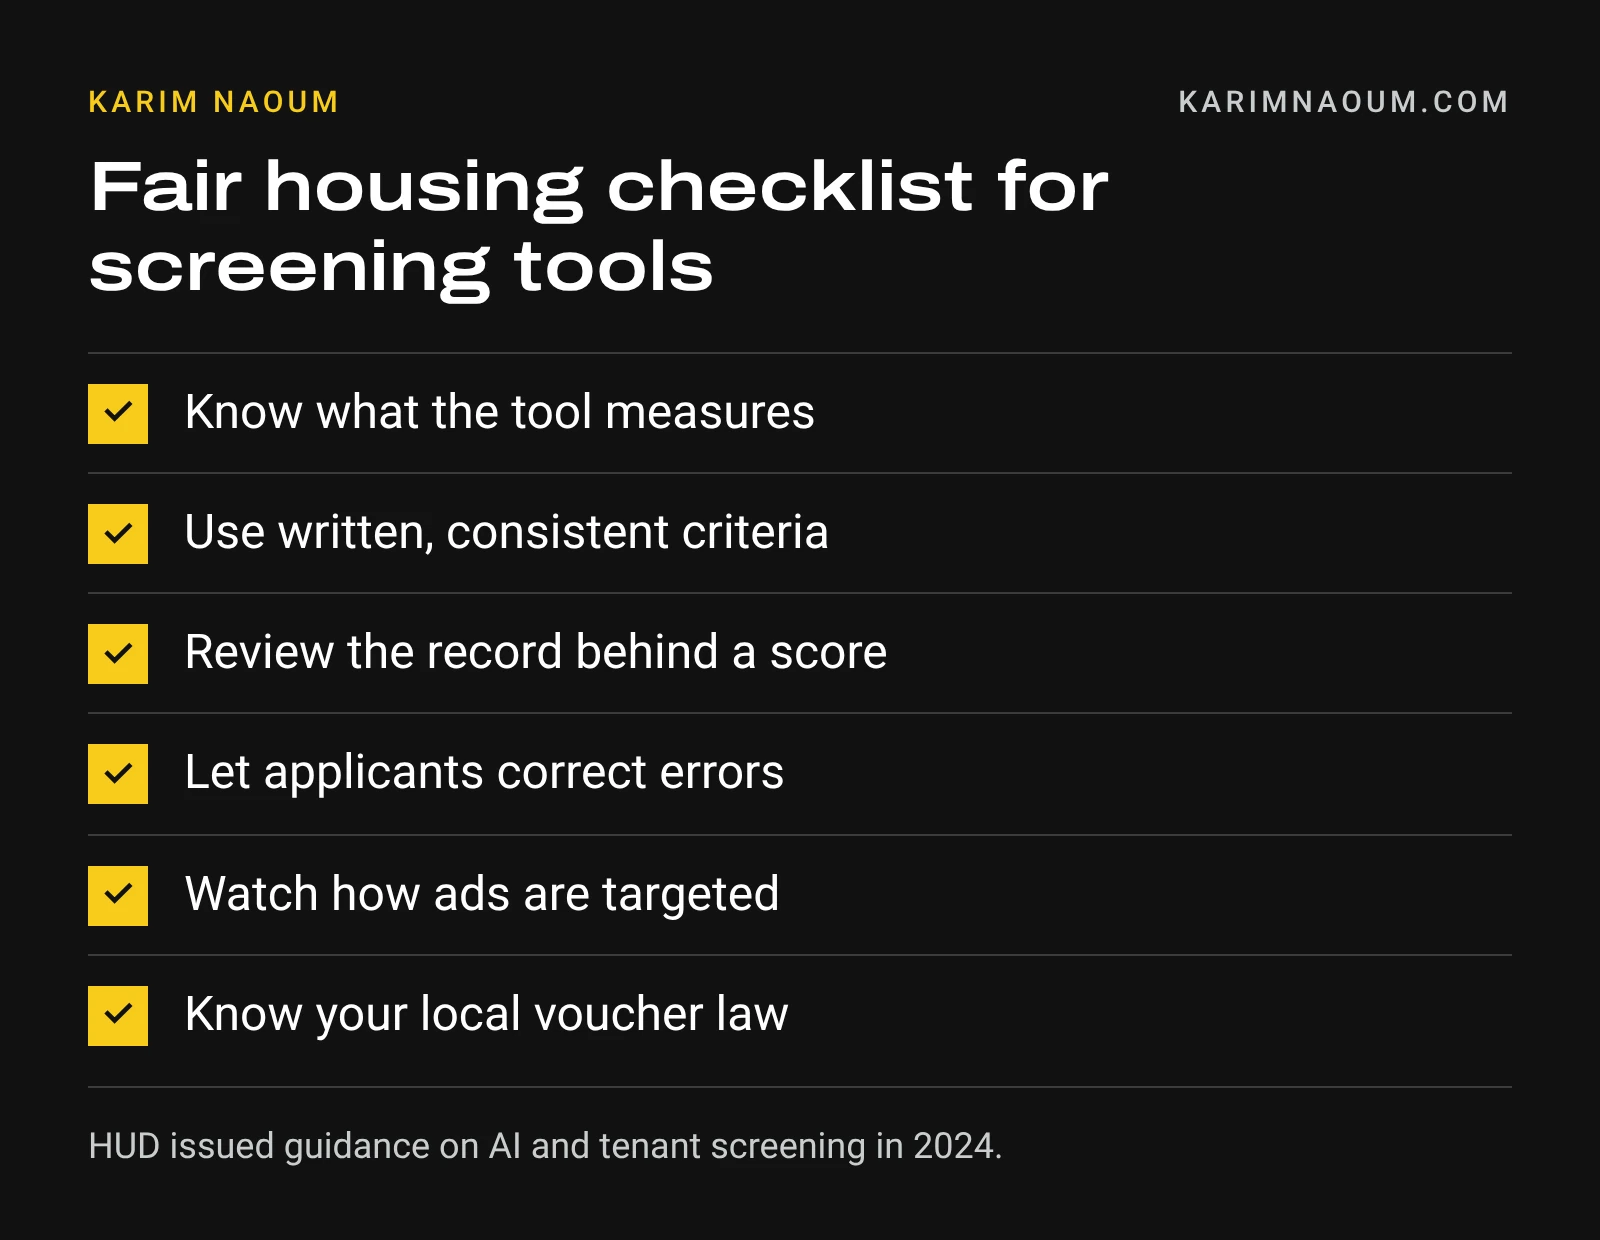
Fair housing checklist for landlords using AI screening tools: know the criteria, apply consistently, review records, allow corrections, watch ad targeting

A simple test for any AI tool

Before paying for a tool, or trusting a free one, ask five questions:

  1. What task does it replace, and how long does that task take now?
  2. How will I check its output? If you can’t verify it, don’t rely on it.
  3. What happens when it’s wrong? A typo in an email is cheap. A wrong rent in a purchase decision isn’t.
  4. What data does it need, and where does that data go?
  5. Does a person stay in the loop for any decision about someone’s housing?

Tools that pass tend to be modest: they summarize, sort, draft, and remind. Tools that promise to replace judgment tend to fail the second question.

What doesn’t change

The parts of rental investing that decide outcomes are the same as they were before any of this existed. Buy at a price the rent supports. Keep the property in good repair. Treat tenants fairly. Hold reserves. Work with the housing agency instead of around it. Karim’s writing on how he thinks about risk and a day in his working life both come back to those basics.

AI can make a careful investor faster. It can’t make a careless one careful.

Explore more of Karim’s thinking

For the principles behind the portfolio, read Karim Naoum’s investing principles and lessons he learned the hard way. If you’re just starting, his advice for beginners covers what to focus on first.
Karim Naoum’s Section 8 Reform Wishlist: Changes That Would Bring More Landlords In

A housing voucher only works if a landlord says yes to it. A family can wait years for assistance, finally receive a voucher, and still lose it because they couldn’t find a unit before the search deadline ran out. That fact should shape any list of Section 8 reform ideas.

That’s why landlord participation matters as much as funding. Karim Naoum has seen the program from both sides. He worked at a local Housing Authority at 17, and as of 2026 his portfolio includes 400+ properties, counting wholly owned properties and partnership interests, most of them leased to families with Housing Choice Vouchers. From an operator’s seat, the reasons owners stay out of the program are practical, and so are the fixes.

This article lays out five Section 8 reform ideas from a landlord’s point of view, what research says about why owners leave, the trade-offs of each change, and what’s already moving.

Why landlords leave the program

The best evidence comes from a study HUD commissioned from researchers at Johns Hopkins University, Urban Landlords and the Housing Choice Voucher Program, published in 2018. The researchers interviewed landlords in Baltimore, Dallas, and Cleveland.

A few findings stand out:

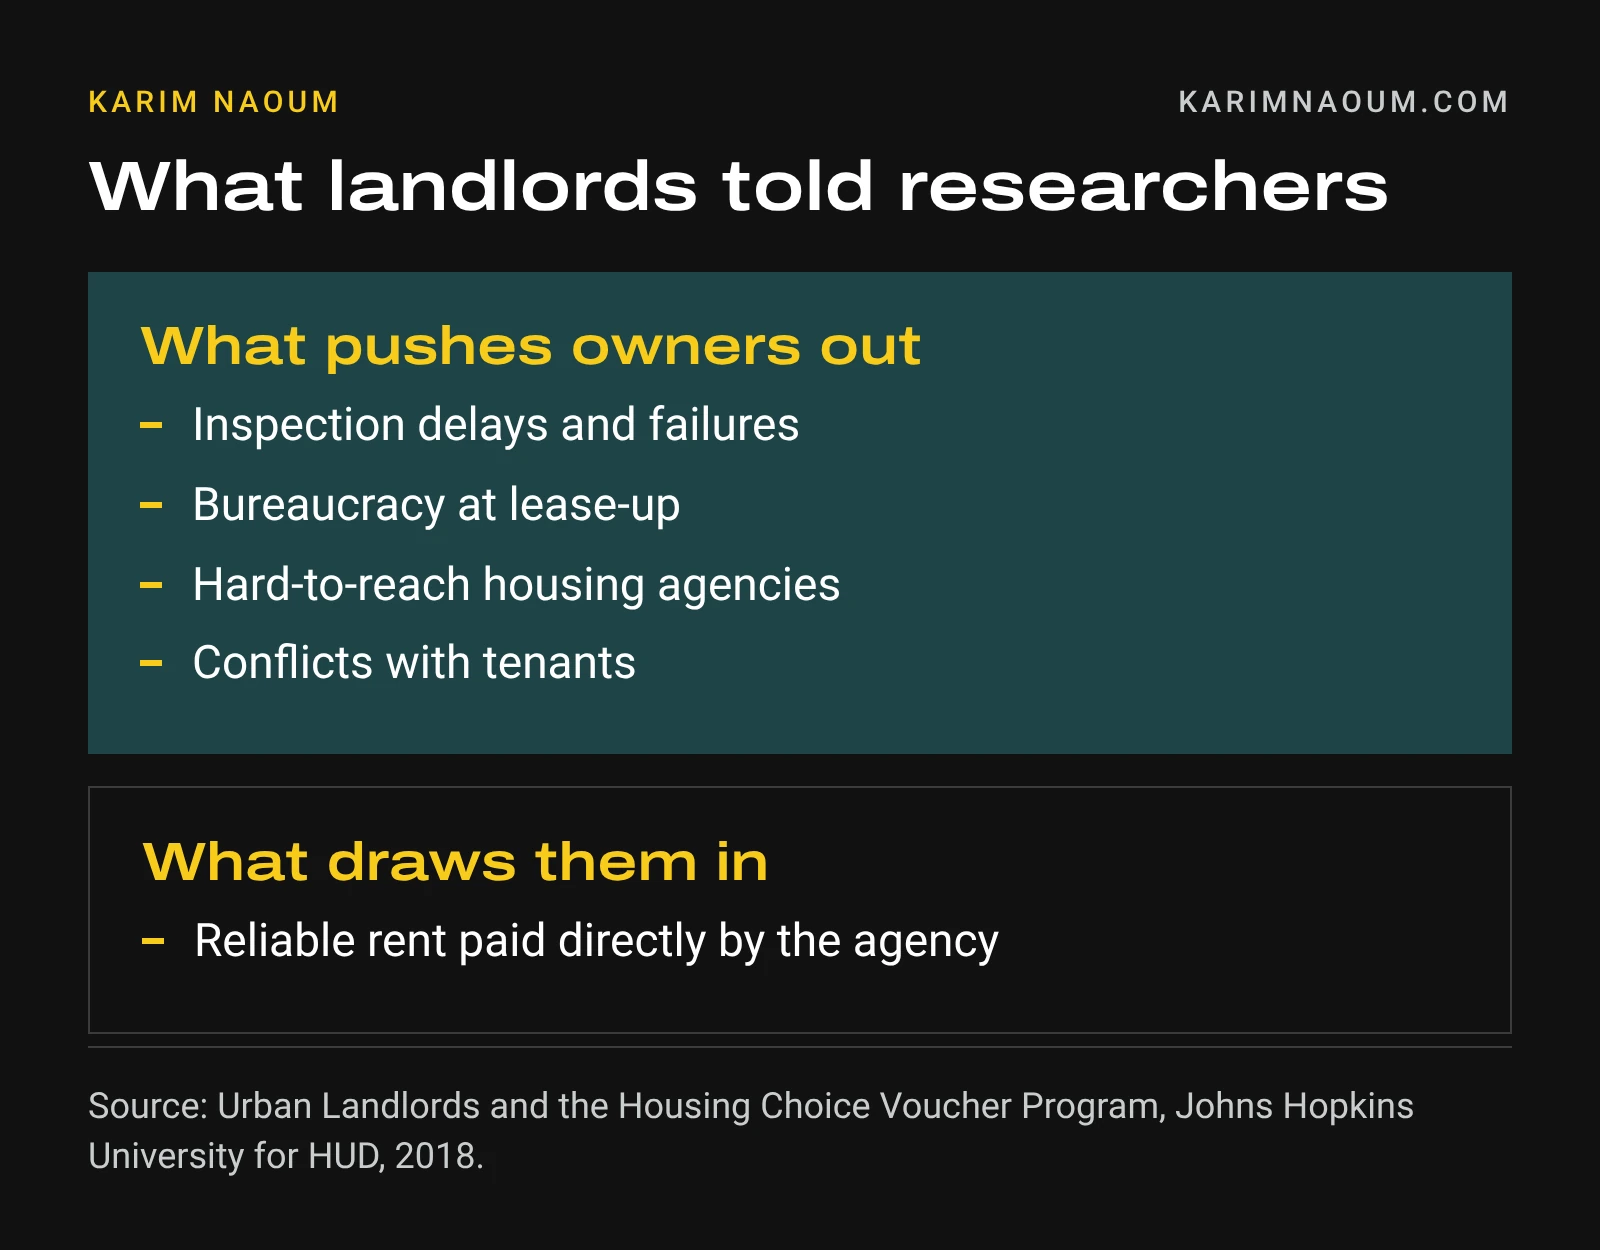
  • Most landlords who refuse vouchers have tried the program before. Their decision usually comes from a bad past experience, not from never having considered it.
  • The frustrations are administrative. Landlords pointed to inspections, bureaucracy, and difficulty dealing with the housing agency during lease-up.
  • Tenant conflicts and stigma play a part. Some owners described disputes with tenants and a sense that the agency wouldn’t back them up. Some simply held negative views of voucher holders.
  • Reliable rent attracts owners. The direct payment from the housing agency was the feature landlords valued most.

Put together, the picture is clear, and it points to which Section 8 reform ideas matter most. The core product, dependable rent, is attractive. The process around it pushes owners away. That’s good news, because process can be fixed without changing who the program serves.

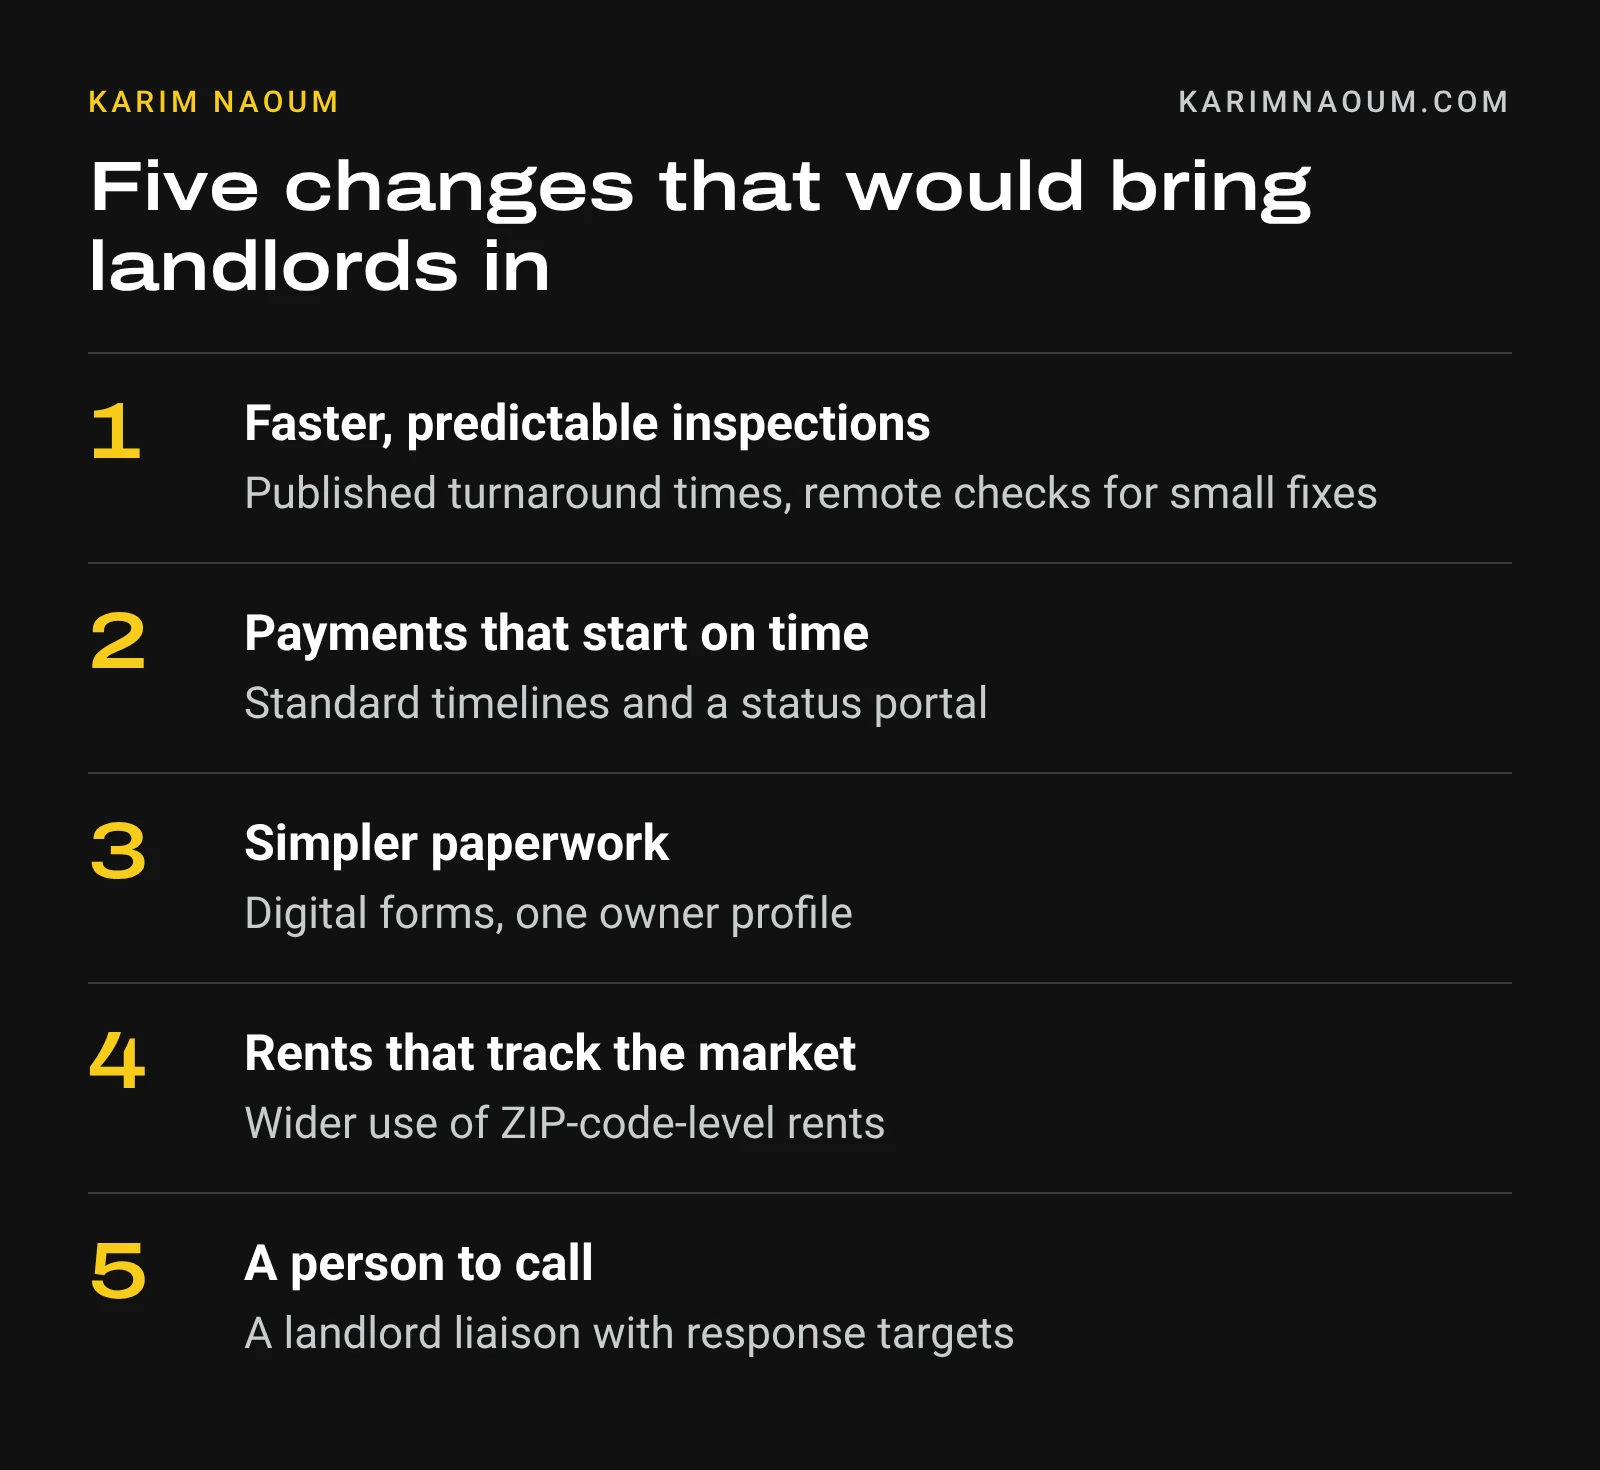
1. Faster, more predictable inspections

Every assisted unit has to pass the housing agency’s inspection before the lease starts. Nobody serious argues against that. Families deserve safe homes, and the standard protects them.

The problem is time. An owner with a vacant, rent-ready unit may wait for the first inspection, fail on a minor item, then wait again for the re-inspection. Each week is lost rent. A market-rate tenant could move in on Saturday.

What would help:

  • Published turnaround targets, so owners can plan.
  • Online scheduling and same-week slots.
  • Remote verification of small fixes, such as photos of a replaced outlet cover, in place of a second visit.
  • Clear checklists shared before the inspection, so owners can pass the first time.

The trade-off: speed can’t come at the cost of safety. Remote verification works for a missing cover plate. It doesn’t work for a furnace. The line has to be drawn carefully.

2. Payments that start on time

Once a tenancy is running, housing assistance payments tend to arrive reliably. That steadiness is the main reason owners join. The weak spot is the beginning. The first payment on a new contract can lag while paperwork is processed, and an ownership change or a rent adjustment can cause a gap.

A new landlord who waits two months for a first payment remembers it.

What would help:

  • A standard timeline from contract signing to first payment.
  • Online portals where owners can see payment status, holds, and reasons.
  • Fast correction of errors and retroactive payments.

The trade-off: agencies run on tight administrative budgets. Better systems cost money up front, even if they save staff time later.

Five Section 8 reform ideas for landlords: faster inspections, on-time payments, simpler paperwork, fair rent setting, and a real point of contact

3. Simpler paperwork

Leasing to a voucher holder involves a Request for Tenancy Approval, the lease, a tenancy addendum, a Housing Assistance Payments contract, owner certifications, and tax and banking forms. Then it differs from one housing agency to the next.

An owner with properties in three jurisdictions learns three sets of forms, three portals, and three sets of deadlines.

What would help:

  • Standard digital forms with e-signature.
  • One owner profile that carries across units, so banking and tax details are entered once.
  • Plain-language guides for first-time landlords.
  • More consistency between agencies, at least within a state or metro area.

The trade-off: local control is part of the program’s design, and agencies do face different conditions. Standardizing the basics doesn’t have to remove that.

4. Rents that track the real market

A voucher rent is limited by the agency’s payment standard and by a rent reasonableness test. Payment standards are built from HUD’s Fair Market Rents. When those numbers lag the market, owners in rising neighborhoods can earn more from a market-rate tenant, and voucher families are pushed toward the areas where rents are lowest.

The Johns Hopkins researchers heard this directly from landlords in Cleveland, many of whom saw voucher rents as below market.

What would help:

  • Wider use of rents set by ZIP code, which HUD calls Small Area Fair Market Rents, so payment standards reflect neighborhood differences.
  • Faster updates when a market moves quickly.
  • Clear explanations when a requested rent is reduced.

The trade-off: this one is real money. Higher payment standards mean each voucher costs more, and with a fixed budget that can mean fewer families served. Policymakers have to balance access to better neighborhoods against the number of households helped.

5. A person to call

The Johns Hopkins study found landlords frustrated by the difficulty of getting answers from housing agencies. When an owner has a problem, whether a payment question, a lease issue, or a concern about a tenancy, not knowing who to call turns a small problem into a reason to leave.

What would help:

  • A landlord liaison or a dedicated owner line with response-time targets.
  • Clear processes for reporting lease violations and getting a decision.
  • Regular owner briefings, in person or online.

Some agencies already do this, and some go further with incentives such as signing bonuses for new landlords or funds to cover damage beyond the security deposit. Owners who feel they have a partner stay. Owners who feel ignored don’t renew.

The trade-off: staff time. A liaison is a salary that isn’t spent on something else.

Why landlords leave Section 8 according to HUD-commissioned research: inspections, bureaucracy, agency communication, tenant conflicts, with reliable rent as the main draw

Section 8 reform ideas already in motion

Reform isn’t starting from zero.

  • Inspection standards are being updated. HUD has been moving agencies from the older Housing Quality Standards to a newer standard called NSPIRE, which focuses more on health and safety and less on cosmetic issues. This guide to NSPIRE inspections explains what changed.
  • Agencies have more flexibility on lease-up. Federal law now lets agencies approve a tenancy when a unit has only non-life-threatening deficiencies, with a deadline to fix them, and to rely on certain other inspections. Whether an agency uses those options is a local decision.
  • Landlord incentives are being tested. HUD has allowed some agencies to try incentives and study whether they bring owners in.
  • More places protect voucher holders from blanket refusals. A growing number of states and cities have laws that bar landlords from rejecting applicants only because they use a voucher.

That last point matters for the wishlist. Rules can require owners to accept voucher applicants, but rules alone don’t make the process work. Places that pair those laws with a faster, friendlier program are likely to see better results than places that rely on enforcement alone.

Where these Section 8 reform ideas have limits

It’s fair to ask whether a landlord’s wishlist serves landlords first. A few honest caveats:

  • Tenants have their own list. Longer search times, help with deposits and moving costs, and protection from discrimination matter as much as anything here.
  • Funding is the bigger constraint. According to the Center on Budget and Policy Priorities, only about one in four eligible households receives federal rental assistance. Smoother administration doesn’t create new vouchers.
  • Owner experience varies. A landlord with hundreds of units and staff has a different experience from an owner with one duplex.

Still, the two sides line up more than they conflict. A family with a voucher needs landlords who say yes. Every change that makes yes easier helps both.

Explore more of Karim’s thinking

These Section 8 reform ideas come from an operator’s view of the program. For the wider picture, read Karim Naoum on Section 8 policy, his outlook on the future of Section 8, and his take on the Section 8 waitlist crisis. If you’re a landlord weighing the program, what every landlord should understand about voucher tenants is the place to start.

Should You Ever Sell a Rental Property? The Buy-and-Hold Case Behind Karim Naoum’s Approach

A few years after buying a rental, many owners hit the same moment. The property has gone up in value. A neighbor sold for a number that sounds great. Maybe a repair bill just landed, or a tenant moved out, and the idea of cashing out and being done starts to look appealing. That is usually when they start asking whether to sell a rental property at all.

So, should you ever sell a rental property? Or is the old advice, buy and never sell, the right one?

Karim Naoum’s portfolio is built around holding. His focus is single-family homes leased to families with Housing Choice Vouchers, bought for monthly cash flow and kept for the long term. As of 2026, his portfolio includes 400+ properties, counting wholly owned properties and partnership interests. That approach reflects a clear view: for a rental that’s doing its job, holding usually beats selling.

Usually isn’t always, though. This article lays out the buy-and-hold case, what selling actually costs, how cash flow tends to grow over time, the situations where selling does make sense, and why refinancing is often the better middle path. It’s not financial advice. It’s the reasoning behind a long-term strategy, so you can test it against your own situation.

Why holding usually wins

Before you sell a rental property, it helps to see what holding it does for you. The buy-and-hold case rests on a simple idea: a good rental pays you to own it, and the longer you own it, the more it tends to pay.

Several things work in your favor the longer you hold:

  • The tenant pays down your mortgage. Each payment reduces your loan balance. Over years, that turns into substantial equity you didn’t contribute directly.
  • Rents tend to rise over time while your fixed-rate mortgage payment stays the same. The gap between rent and payment is cash flow, and it tends to widen.
  • You keep depreciation deductions. Owners can generally deduct the building’s cost over time, which often reduces taxable rental income. A CPA should advise on your specifics.
  • You avoid transaction costs. Every sale and purchase costs money. Holding avoids them.
  • You keep a performing asset. Finding a good replacement property isn’t guaranteed, especially in a competitive market.

That last point is easy to underrate. If you sell a property that cash flows reliably, you’ll need to find, finance, inspect, repair, and lease up another one to replace that income. That’s real work and real risk.

Holding is also central to how Section 8 rentals work best. Voucher tenants often stay for years, partly because moving with a voucher involves paperwork and inspections. A stable tenancy in a well-kept home is exactly the kind of asset that rewards patience. Karim’s broader rules for buying and holding are collected in Karim Naoum’s investing principles.

What it really costs to sell a rental property

The price a property sells for isn’t what you keep. Owners who look only at the headline number often overestimate what they’ll walk away with.

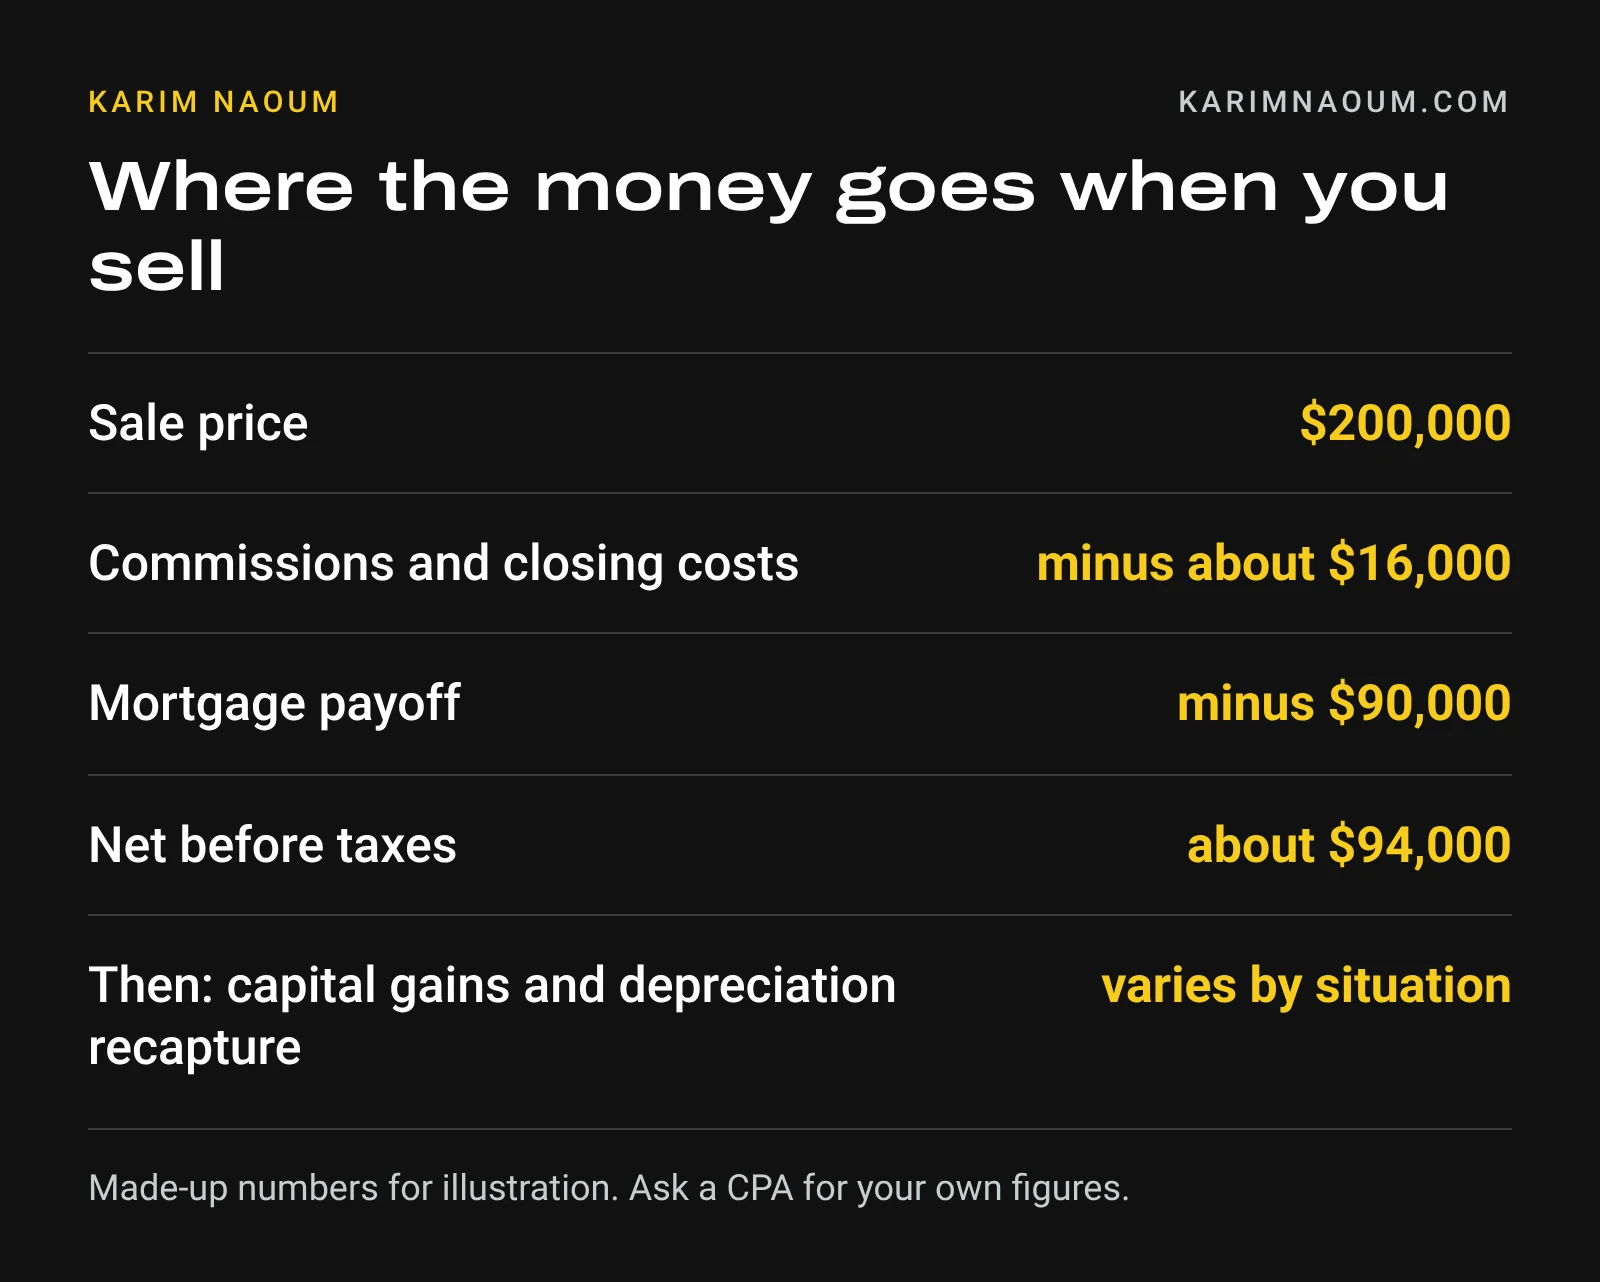
Where the money goes when you sell a rental property: commissions, closing costs, loan payoff, and taxes

Selling a rental typically involves:

  • Agent commissions, often a significant percentage of the sale price
  • Closing costs, including title, transfer taxes, and attorney or escrow fees, which vary by state
  • Repairs or concessions to get the property sold, especially if it’s been a rental for years
  • Vacancy while it’s on the market, if you sell it empty
  • Paying off the mortgage
  • Capital gains tax on the profit
  • Depreciation recapture, which taxes the depreciation you’ve deducted over the years, often at a higher rate than long-term capital gains

Here’s a simple illustration, using made-up numbers. Say you bought a rental years ago, and it would now sell for $200,000. You owe $90,000 on the mortgage. Selling costs, including commissions and closing costs, come to about $16,000. You’d net about $94,000 before taxes.

Then the taxes. If your adjusted basis, after years of depreciation, is well below the sale price, part of your gain is taxed as depreciation recapture and the rest as capital gain, plus any state tax. Depending on your situation, the tax bill could take a meaningful share of that $94,000.

Meanwhile, if that property was producing a few hundred dollars a month of cash flow, with the tenant paying down the loan every month, you’ve traded a growing income stream for a one-time check that’s smaller than the headline price suggested.

Cash flow that grows over time

One reason not to sell a rental property early is that its cash flow tends to improve with time. The part of buy-and-hold that’s hardest to see in year one is how much better a rental tends to look in year ten.

Consider how the numbers shift on a property with a fixed-rate mortgage:

  • Year 1: Rent barely exceeds the mortgage, taxes, insurance, and reserves. Cash flow is thin.
  • Year 5: Rent has increased a few times, with approval from the housing agency at lease anniversaries. The mortgage payment hasn’t changed. Cash flow is noticeably better.
  • Year 15: The loan balance is much lower, rent has kept rising, and the gap between them is substantial.
  • Payoff: Once the mortgage is gone, nearly all the rent minus operating costs is income.

Operating costs rise too, especially taxes and insurance, so it’s not a straight line. But the principle holds: on a fixed-rate loan, your largest expense stays flat while rent tends to grow.

For Section 8 rentals, rent increases go through the housing agency, typically at the lease anniversary, and must be reasonable compared with similar unassisted units in the area. That keeps increases tied to the local market rather than the owner’s wishes.

This is why many long-term investors say their best rental is their oldest one. To see how that played out across a portfolio built over time, read the story of how Karim Naoum built his business.

When you should sell a rental property

Buy-and-hold is a default, not a rule. There are good reasons to sell a rental property, and a smart hold strategy includes knowing when to let one go.

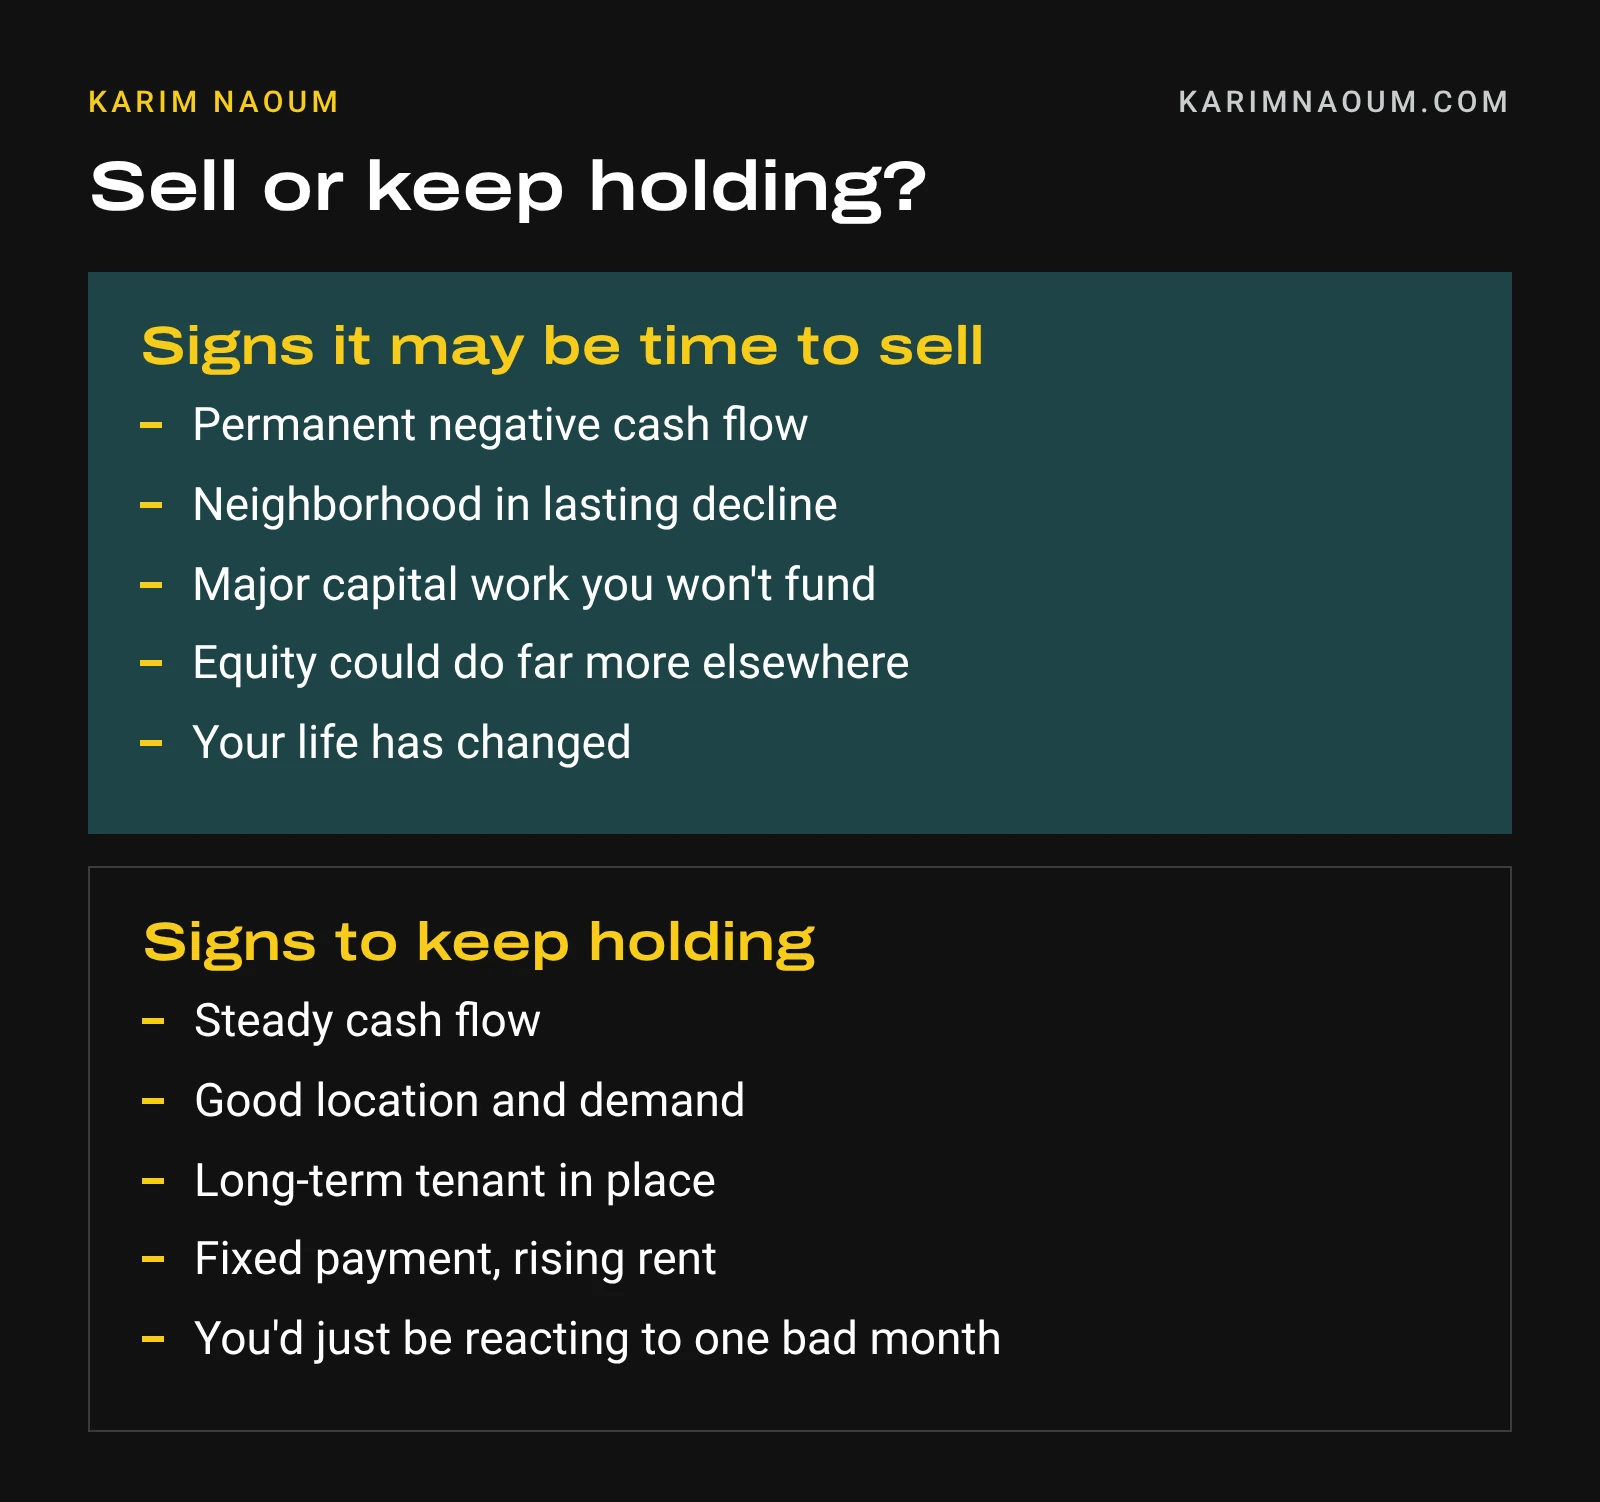
Signs it may be time to sell a rental property versus signs you should keep holding

The property no longer cash flows, and won’t. If rising taxes, insurance, or repairs have pushed a property into permanent negative cash flow with no realistic fix, holding it is just slowly losing money.

The neighborhood is in sustained decline. Falling demand, rising crime, or a major employer leaving can make a property harder to rent and harder to sell later.

The property needs major capital work you won’t fund. A roof, foundation, sewer line, and HVAC all failing in the same few years can cost more than the property earns.

It’s a constant management problem. Some properties generate far more stress, calls, and turnover than their income justifies. Your time has value.

Bigger-picture reasons to sell

Your equity could work much harder elsewhere. If a property has appreciated dramatically but produces modest income, the equity might generate more cash flow in other properties. A 1031 exchange, which defers taxes when you reinvest sale proceeds in other investment real estate, is how many investors make that move. The IRS explains the rules in its guide to like-kind exchanges.

Your life has changed. Retirement, health, family needs, or simply wanting out of being a landlord are legitimate reasons. Investing serves your life, not the other way around.

Concentration risk. If one property or one market makes up too much of your net worth, selling part of it to diversify can be prudent.

The difference between a good sale and a bad one usually comes down to why you’re selling. Selling a problem property or repositioning equity on purpose is strategy. Selling a good property because of one bad month or a tempting number is often a mistake you can’t undo.

Refinancing instead of selling

Not everyone who wants cash needs to sell a rental property. For owners who want access to their equity without giving up the property, refinancing is often the middle path.

A cash-out refinance replaces your current mortgage with a larger one and gives you the difference in cash. You keep the property, the tenant, and the income. The cash can fund repairs, reserves, or down payments on additional rentals.

Refinancing has trade-offs:

  • Your payment usually goes up, which reduces cash flow, especially if current rates are higher than your existing loan.
  • There are closing costs, though usually less than selling.
  • You’re adding debt, which raises your risk if rents fall or a property sits vacant.

Many investors use refinancing to grow, borrowing against appreciated properties to buy more, rather than selling. It’s a powerful tool when used carefully and a dangerous one when used to stretch too far. Investors who refinance into DSCR loans, which qualify a property based on its rent, benefit from clean rent records and a property in good condition. How Karim thinks about debt and the downside of over-borrowing is explained in Karim Naoum on risk in real estate.

Selling with seller financing is another option some owners consider, since it can spread the gain over several years and turn the property into monthly note income. Buyers and sellers both need to understand the terms. An attorney and a CPA should review any seller-financed sale before you agree to it.

Questions to ask before you sell a rental property

Before you put a rental on the market, work through these:

  1. What will I actually net after commissions, closing costs, loan payoff, and taxes? Get real numbers from an agent and a CPA.
  2. What does this property earn now, and what will it likely earn in five years?
  3. What would I do with the money? If you’d reinvest it, could you realistically find something better?
  4. Is the problem the property or the management? A better property manager sometimes solves what feels like a property problem.
  5. Could a refinance or a 1031 exchange get me what I want without a full sale?
  6. Am I reacting to one bad month, or a lasting change?
  7. How does this fit my overall plan, including retirement, estate plans, and how much time I want to spend on real estate?

If you’re still holding, make sure the property is being run well. Owners who stay on top of maintenance, inspections, and tenant communication tend to find holding much easier. This guide to Section 8 landlord responsibilities covers what that involves.

The bottom line

Should you ever sell a rental property? Sometimes, yes. Sell when a property can’t be fixed, when the neighborhood is in lasting decline, when the equity can do much more elsewhere, or when your life calls for it.

But for a rental that’s cash flowing, well located, and reasonably managed, the buy-and-hold case is strong. The tenant keeps paying down the loan, rent tends to rise while a fixed payment stays flat, and you avoid the costs and taxes that come with selling. That’s the reasoning behind a portfolio built to hold, and it’s why Karim’s approach treats selling as the exception rather than the plan.

Explore more of Karim’s thinking

Whether to sell a rental property is one decision inside a longer strategy. To understand the rules behind a long-term strategy, start with Karim Naoum’s investing principles and his perspective on rental real estate vs the stock market. For the mistakes that shaped his approach, read lessons Karim Naoum learned the hard way in real estate.

Karim Naoum on the Ethics of Profiting From Affordable Housing

Anyone who builds a business around Section 8 rentals eventually hears the question, and Karim Naoum hears it more than most. Is it ethical to be a Section 8 landlord? Is it right to make money from a program designed to help low-income families afford a home?

It’s a fair question, and it deserves a straight answer rather than a defensive one. This article lays out the criticism as its strongest critics would put it, what the voucher program actually needs from private owners, where landlords genuinely fall short, and the standards that the approach behind Karim’s work is built on.

Is it ethical to be a Section 8 landlord? The criticism, stated fairly

Critics usually frame the case against Section 8 investing like this.

The Housing Choice Voucher program is funded by taxpayers to help families who can’t afford market rents. When investors buy homes specifically to rent to voucher holders, part of that public money becomes private profit. Critics argue this is backwards: public dollars meant for families end up building investors’ wealth.

There’s a sharper version too. Some landlords treat the voucher program as a guaranteed check. They rent units that barely pass inspection, put off repairs, and rely on tenants having few other options. Critics point out that voucher holders often face long waits, limited choices, and discrimination from owners who won’t accept vouchers at all, which gives landlords bargaining power that tenants don’t have.

And there’s a broader concern about real estate education. When programs market Section 8 as easy money, critics worry they attract people who care about cash flow and little else.

These criticisms aren’t made up. Each one describes something that really happens. Any honest defense of Section 8 investing has to start by admitting that.

What the program needs from private owners

Any honest answer to whether it is ethical to be a Section 8 landlord has to start with how the program works. Here’s the part of the debate that often gets lost.

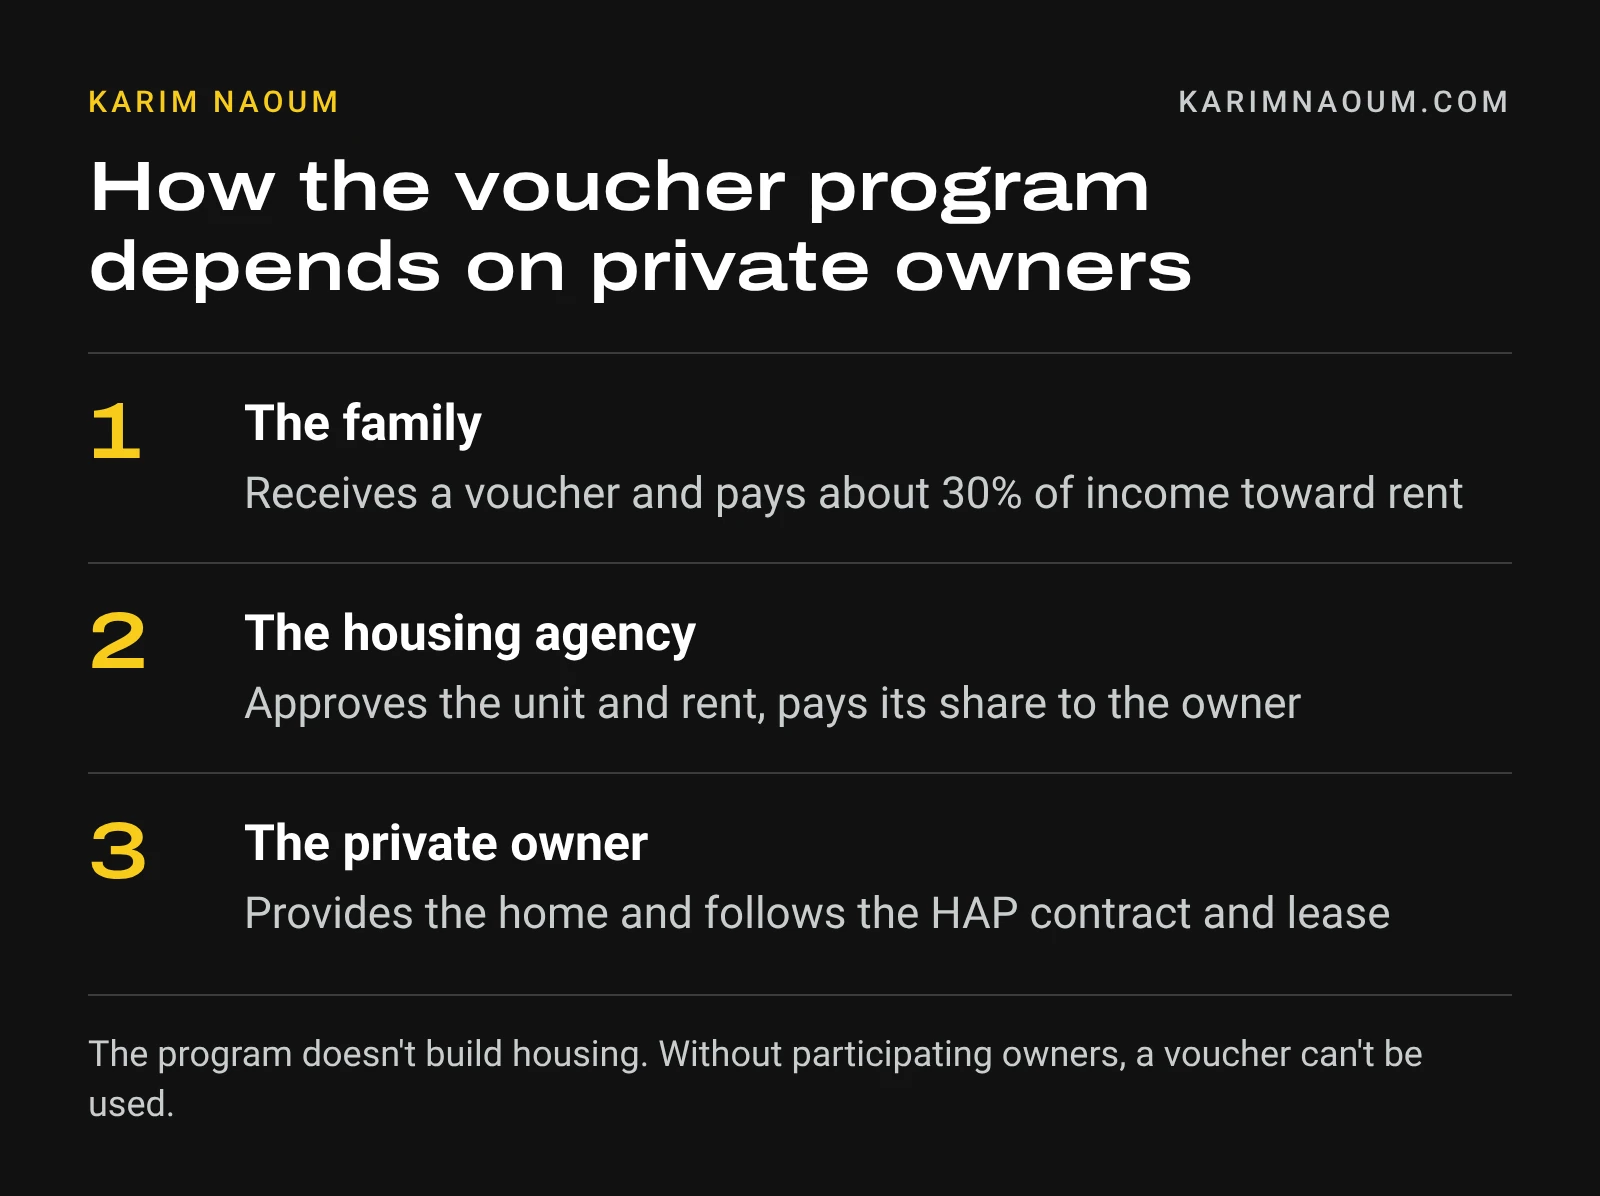
The Housing Choice Voucher program doesn’t build housing. It gives eligible families a voucher that helps pay rent in the private market. That only works if private owners are willing to rent to them. A voucher with no landlord willing to accept it is just a piece of paper, and many families with vouchers struggle to find a unit before their search time runs out.

That’s not a side effect of the program. It’s the design. Congress built the voucher system around private owners, and the program depends on enough of them participating.

Demand far outstrips supply. The Center on Budget and Policy Priorities reports that federal rental assistance reaches only about 1 in 4 households that are likely eligible. The families who do receive vouchers are often among the most vulnerable. In California, for example, the Disability Rights Education and Defense Fund notes that more than half of vouchers serve elderly or disabled households.

Seen this way, the question shifts. If the program needs private landlords, then the question isn’t whether landlords should earn a return. Almost no one rents out property at a loss for long. The real question is whether they earn it by providing safe, decent housing and treating tenants fairly.

How the Housing Choice Voucher program depends on private landlords: family, housing agency, and owner

Where a Section 8 landlord can fall short

Defending Section 8 investing doesn’t mean defending every Section 8 landlord. Some of the criticism is earned, and it’s worth naming where owners fail.

Minimum-standard housing. Passing inspection is a floor, not a goal. Some owners do the least possible to pass, then wait for the next inspection to fix anything.

Slow repairs. A broken heater in January is an emergency for a family, regardless of who pays the rent. Owners who drag their feet on repairs are failing their tenants, whether or not the agency catches it.

Treating tenants as interchangeable. Voucher households are families with jobs, kids, health conditions, and lives. An owner who sees them only as a payment stream will make worse decisions about everything from communication to maintenance.

Side payments and shortcuts. Charging tenants extra money outside what the housing agency approved isn’t just unethical. It’s a serious program violation.

Discrimination. Refusing to rent to voucher holders is still common, and in many states and cities it’s illegal. Treating voucher tenants worse than market-rate tenants is a failure too.

Karim has been direct that the industry, including real estate education, has problems worth criticizing. His fuller response to critics of his business and his teaching is in Karim Naoum answers his critics.

The standards behind his approach

For Karim, being an ethical Section 8 landlord comes down to a few standards. If profit isn’t the problem, how an owner earns it is. The approach Karim teaches and invests by rests on a few standards that are simple to state and harder to follow consistently.

Housing you’d be comfortable living in. The unit should be safe, clean, and functional, not just inspection-ready on the day the inspector visits.

Repairs on time. Urgent problems get handled urgently. Routine problems get handled before they become urgent.

Following the rules, all of them. That means following the HAP contract, the lease, the tenancy addendum, fair housing law, and local landlord-tenant law. No side payments. No shortcuts.

Clear communication. Tenants should know how to reach the owner or manager and should get a response.

Working with the agency, not against it. Karim worked at a local Housing Authority at 17 and saw the program from the agency’s side: how inspections, paperwork, and payments actually move. Owners who understand that system tend to cooperate with it, which makes the process smoother for tenants as well as owners.

Honest marketing. Section 8 investing isn’t easy money, and it shouldn’t be sold that way. Programs that oversell it attract the wrong owners. Karim’s views on clear, honest claims in his industry are explained in Karim Naoum on transparency in real estate education.

For a practical look at what the program expects of every participating owner, this guide to Section 8 landlord responsibilities lays out the obligations in detail.

What accountability looks like for an ethical Section 8 landlord

Standards only matter if something enforces them. In the voucher program, accountability comes from several directions.

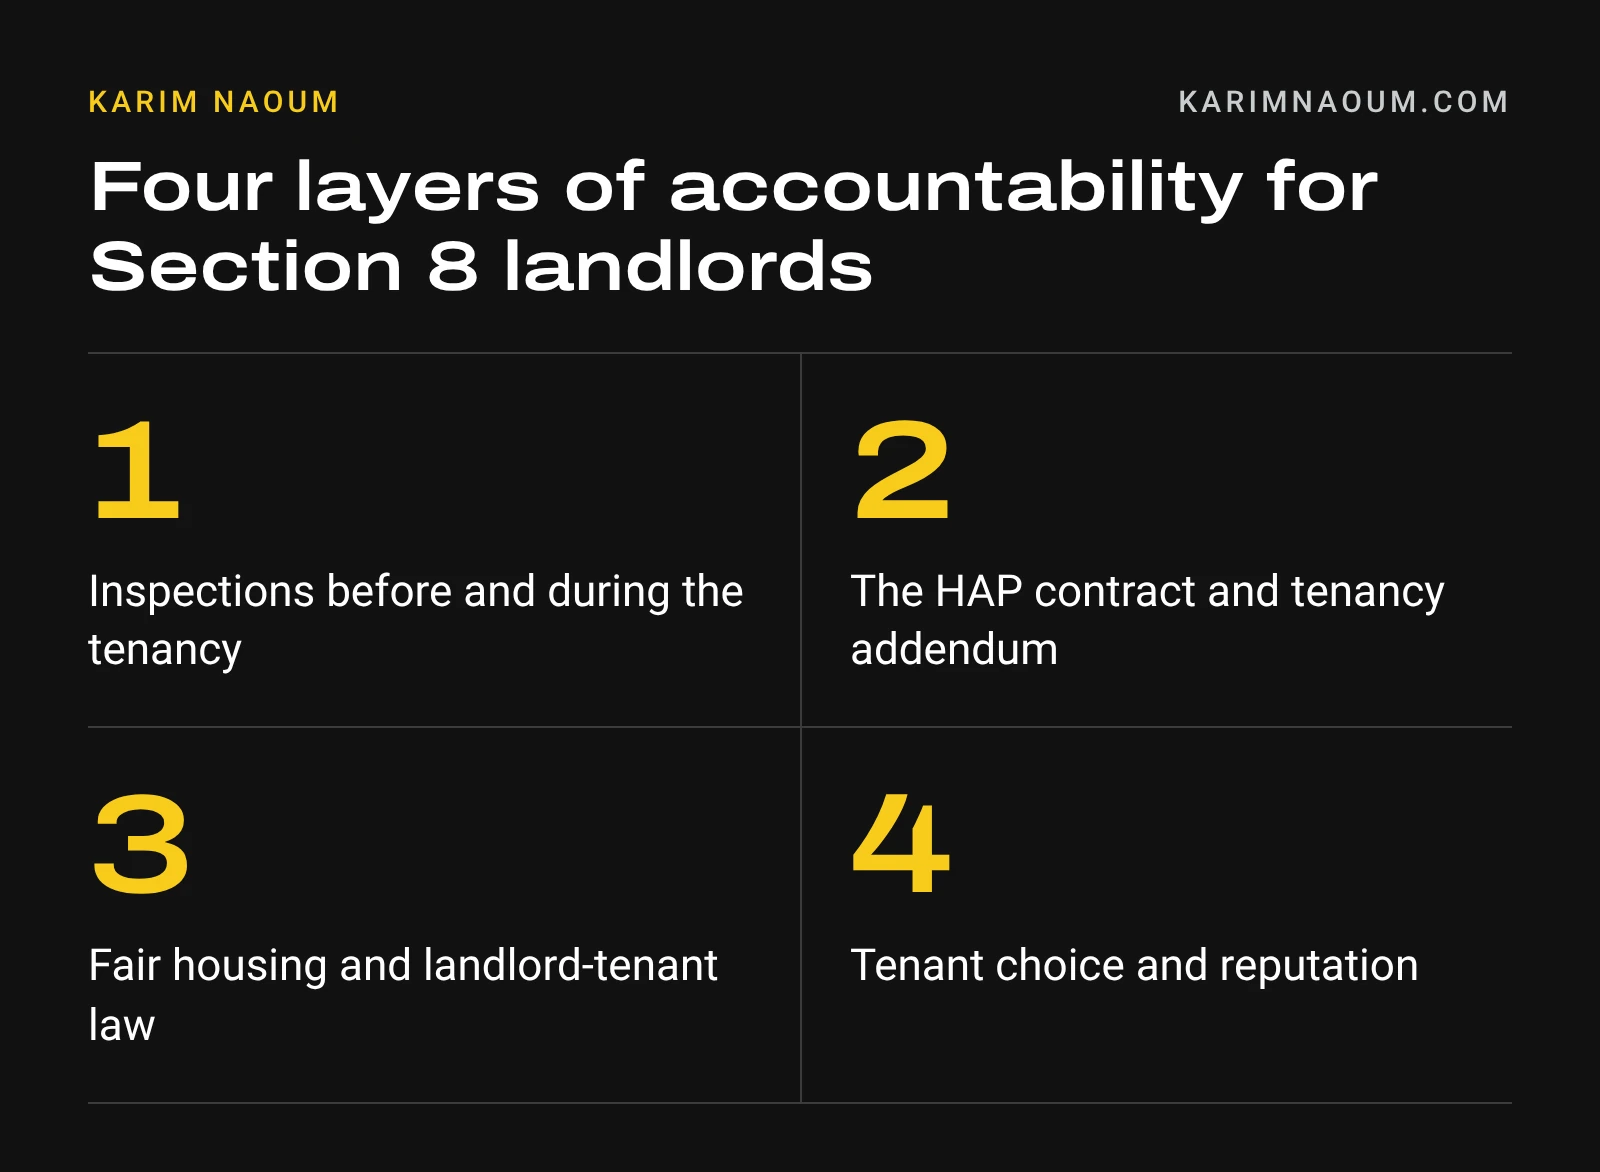
Four layers of accountability for Section 8 landlords: inspections, contracts, law, and reputation

Inspections. Housing agencies inspect units before a tenancy starts and periodically after. If a unit fails, the owner has to fix it, and agencies can stop payments until it’s corrected.

The HAP contract. Owners sign a contract with the agency that spells out their obligations. Breaking it can end the contract and the owner’s participation.

Fair housing and landlord-tenant law. Voucher tenants have the same legal protections as any other tenant, and in many places, additional protection against discrimination based on their source of income.

Tenant choice. Families with vouchers can move when their lease allows. Owners who maintain good homes and treat people well keep tenants for years. Owners who don’t, lose them.

Reputation. Housing agency staff, tenants, and other landlords talk. Owners known for poor conditions find the process harder over time.

Accountability also has to come from inside. An owner who would only maintain a property because an inspector is coming isn’t the kind of owner the program needs. The standard should be the same whether the rent comes from a voucher or a private paycheck.

Common questions about Section 8 and profit

People asking whether it is ethical to be a Section 8 landlord usually have a few practical questions too. Do Section 8 landlords get paid more than market rent?
Not by design. The housing agency has to approve the rent as reasonable compared with similar unassisted units nearby, and the total has to fit within the local payment standard. In some areas that’s close to market rent. In others it’s below.

Who pays the rest of the rent?
The family pays its share, typically about 30% of its adjusted income, and the agency pays the remainder directly to the owner.

Can a landlord charge a voucher tenant extra?
No. Charging more than the approved tenant share is a program violation.

So, is it ethical to be a Section 8 landlord?

The answer behind Karim’s work is that profiting from affordable housing isn’t the ethical problem. Providing poor housing is.

The voucher program was built to rely on private owners, and it needs more of them. An owner who provides a safe, well-maintained home, follows the rules, treats tenants with respect, and earns a fair return is doing exactly what the program was designed to encourage. An owner who cuts corners, delays repairs, or takes advantage of tenants’ limited options is failing, whether they make money or not.

That standard applies to Karim’s own business and to the investors he teaches. Some critics will never accept that profit and affordable housing belong together, and that’s a reasonable position to hold about the program’s design. But as long as the program depends on private landlords, the more useful question is what kind of landlords it gets.

His broader reasoning for choosing Section 8 over other real estate strategies is in Section 8 investing: why I choose it over other real estate strategies.

Explore more of Karim’s perspective

The question of whether it is ethical to be a Section 8 landlord connects to everything else Karim writes about. If this question matters to you, as an investor, a critic, or someone weighing the program, there’s more to read. Start with Karim Naoum’s response to his critics, then his thoughts on the future of Section 8 investing. For the full story of how his background at a Housing Authority shaped his work, read the Karim Naoum biography.

Rental Real Estate vs the Stock Market: The Case Behind Karim Naoum’s Section 8 Strategy

Real estate vs stocks is one of the oldest arguments in personal finance, and it rarely gets an honest answer. Real estate investors tend to talk about stocks as a casino. Index fund fans tend to talk about landlords as people who bought themselves a second job. Still, both sides have a point, and both leave things out.

Karim Naoum, known online as Section 8 Karim, built his business around rental real estate, specifically single-family homes leased to families using Housing Choice Vouchers. His portfolio includes 400+ properties as of 2026, counting wholly owned properties and partnership interests. So it’s fair to ask: why rentals? What does that approach offer that the stock market doesn’t, and what does it give up?

Instead, this article compares the two fairly. It covers the core difference, cash flow versus market swings, how debt changes the picture, the effort each one takes, what stocks honestly do better, and why many investors end up doing both. It’s not financial advice. It’s the reasoning behind a strategy, laid out so you can judge it against your own situation.

Real estate vs stocks: the core difference

When you buy a stock or an index fund, you own a small slice of businesses. You make money when those businesses grow and their share prices rise, and sometimes through dividends. However, you don’t run anything. Buying or selling takes seconds.

When you buy a rental property, you own a physical asset that produces income because someone lives in it and pays rent. You make money from that rent, from paying down the mortgage over time, and from any rise in the property’s value. You’re responsible for the property, or for hiring people who are. Selling takes weeks or months and costs real money.

As a result, that difference shapes everything else. Stocks are a passive ownership stake you can’t control. Rentals are an operating asset you can influence, for better or worse.

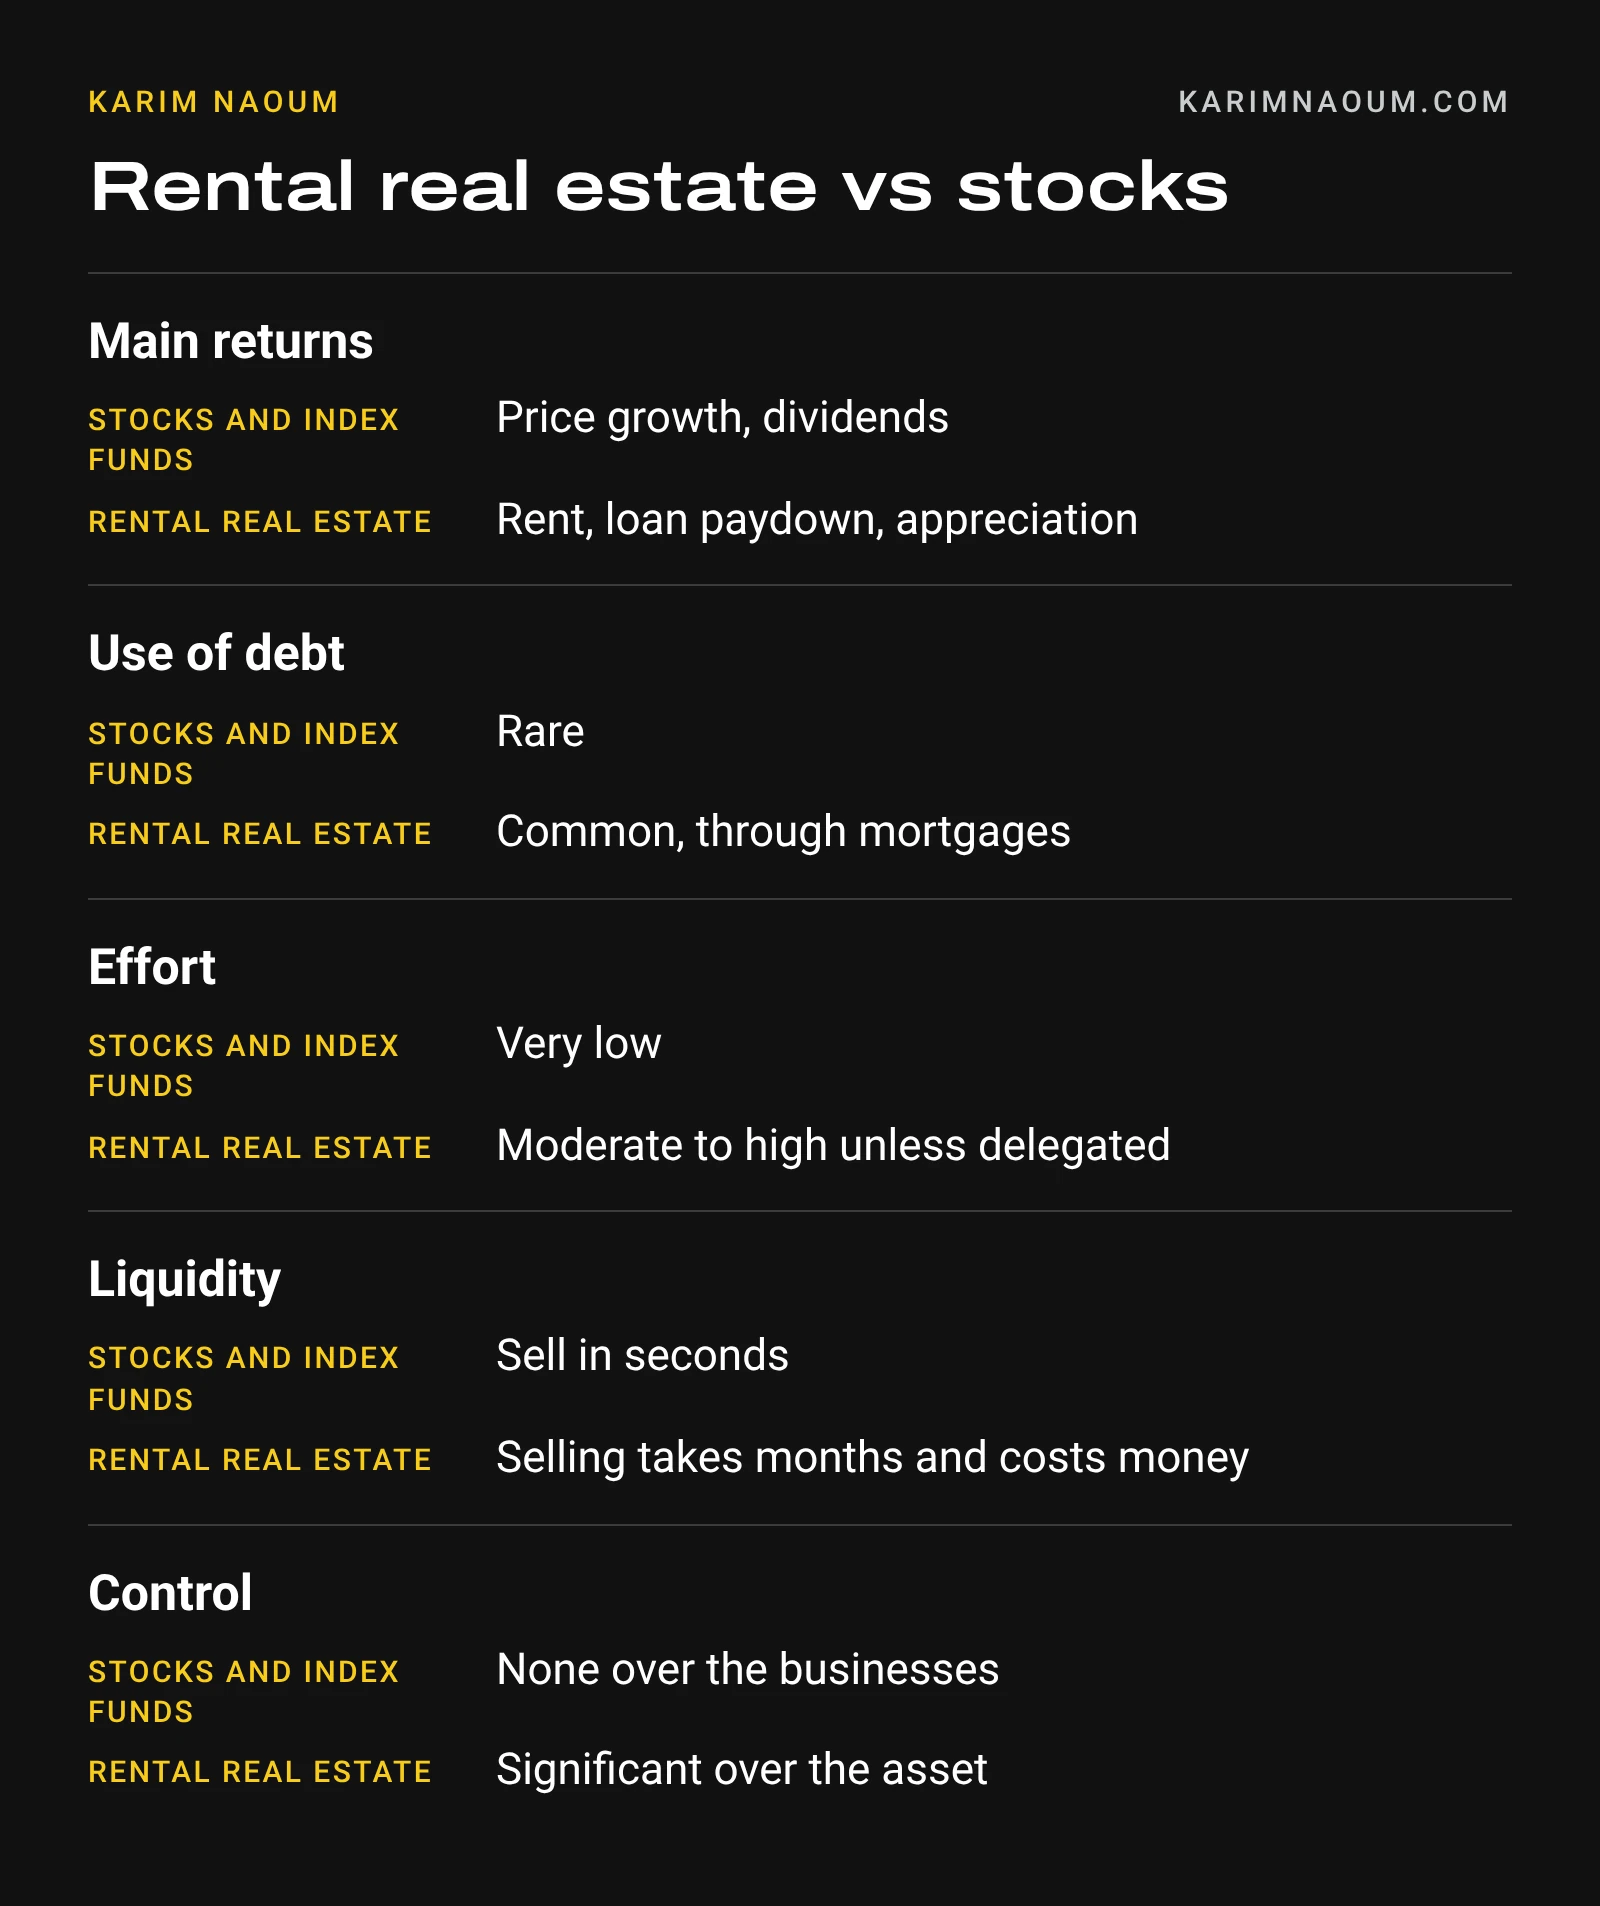
Stocks and index fundsRental real estate
What you ownShares of businessesA physical property
Main return driversPrice growth, dividendsRent, loan paydown, appreciation, tax benefits
Typical use of debtRare for most investorsCommon, through mortgages
EffortVery lowModerate to high, unless delegated
LiquidityHigh, sell in secondsLow, selling takes time and costs money
ControlNone over the businessesSignificant over the asset
Minimum to startVery lowTypically thousands for a down payment and reserves
DiversificationEasy, one fund can hold hundreds of companiesHarder, each property is a big single bet
Side-by-side comparison of rental real estate vs stocks on cash flow, debt, effort, liquidity, and control

Cash flow vs market swings

In the real estate vs stocks debate, cash flow is where the two differ most. The biggest reason rental investors choose real estate is cash flow: money that arrives every month, whatever the market is doing.

For example, stock prices move every day. Over long periods, broad stock indexes have grown, but the ride includes sharp drops, and investors who need to sell during a downturn can lock in losses. Dividends provide some income, but for most index funds, the yield is small compared with the growth investors are counting on.

A rental, by contrast, is different. If the rent covers the mortgage, taxes, insurance, repairs, and management with money left over, the property pays you while you own it, whether its market value went up or down that year. In other words, you don’t have to sell anything to get paid.

That’s the logic behind a cash-flow-first approach, and it’s central to how Karim invests. In the voucher program, a large share of the rent typically comes from the housing agency’s payment, deposited directly each month as long as the unit stays in compliance. For an owner focused on steady income, that predictability is a big part of the appeal. His case for choosing Section 8 over other real estate strategies is laid out in Section 8 investing: why I choose it over other real estate strategies.

There’s a trade-off, though. Cash flow from rentals isn’t guaranteed. A vacancy, a failed inspection, a roof replacement, or a rise in taxes and insurance can turn a profitable month into a costly one. Rental income is steadier than stock prices, but it isn’t automatic.

Leverage and debt

Debt is the biggest structural gap in real estate vs stocks. Debt is where real estate and stocks differ most, and where the rental case is both strongest and riskiest.

First, most rental investors use mortgages. If you buy a $120,000 house with $30,000 down and a loan for the rest, your $30,000 controls a $120,000 asset. If the property rises in value by 5%, that’s $6,000, which is a 20% gain on your cash. The tenant’s rent pays down the loan over time, building equity you didn’t have to contribute yourself.

On the other hand, most stock investors don’t borrow to invest, and for good reason. Borrowing against stocks can force you to sell at the worst time if prices fall.

Mortgage debt on rentals works differently because it’s long-term and isn’t called due just because the property’s value dips. Still, debt cuts both ways:

  • If values fall, your losses are magnified the same way gains would be.
  • If rent stops, the mortgage doesn’t. Reserves matter more when you carry debt.
  • Rates matter. Higher borrowing costs can erase cash flow on deals that would have worked a few years earlier.

Karim has spoken publicly about using DSCR loans, which qualify a property based on its rental income rather than the owner’s personal income. That’s one way investors scale a rental portfolio, and it’s also why disciplined underwriting and reserves are non-negotiable. How he thinks about debt and downside is covered in detail in how Karim Naoum thinks about risk in real estate.

Control and effort

Effort is the cost side of real estate vs stocks that people tend to skip. With stocks, you can’t fix a bad CEO. With a rental, you can fix a leaking roof, change property managers, improve the unit, or adjust how you screen tenants. That control is a real advantage for investors who want to influence their results.

It’s also real work. Someone has to find the property, analyze it, finance it, repair it, lease it, handle maintenance calls, deal with the housing agency, and keep records for taxes. Most experienced investors delegate much of that to property managers and contractors, but they still oversee the business. In short, a rental portfolio is closer to running a small company than to owning a fund.

For Section 8 rentals specifically, effort includes working with the housing agency on inspections, rent approvals, and paperwork. Karim worked at a local Housing Authority at 17, where he saw that process from the agency’s side, and understanding it has been central to how he invests and teaches. For investors who learn the system, it becomes routine. For those who don’t, it’s a source of delays.

If you want a hands-off investment, stocks win this category easily. If you’re willing to build or hire a team, the effort becomes manageable, and the control becomes an advantage.

Real estate vs stocks: what stocks do better

An honest comparison has to give stocks their due. In several areas, they’re simply better.

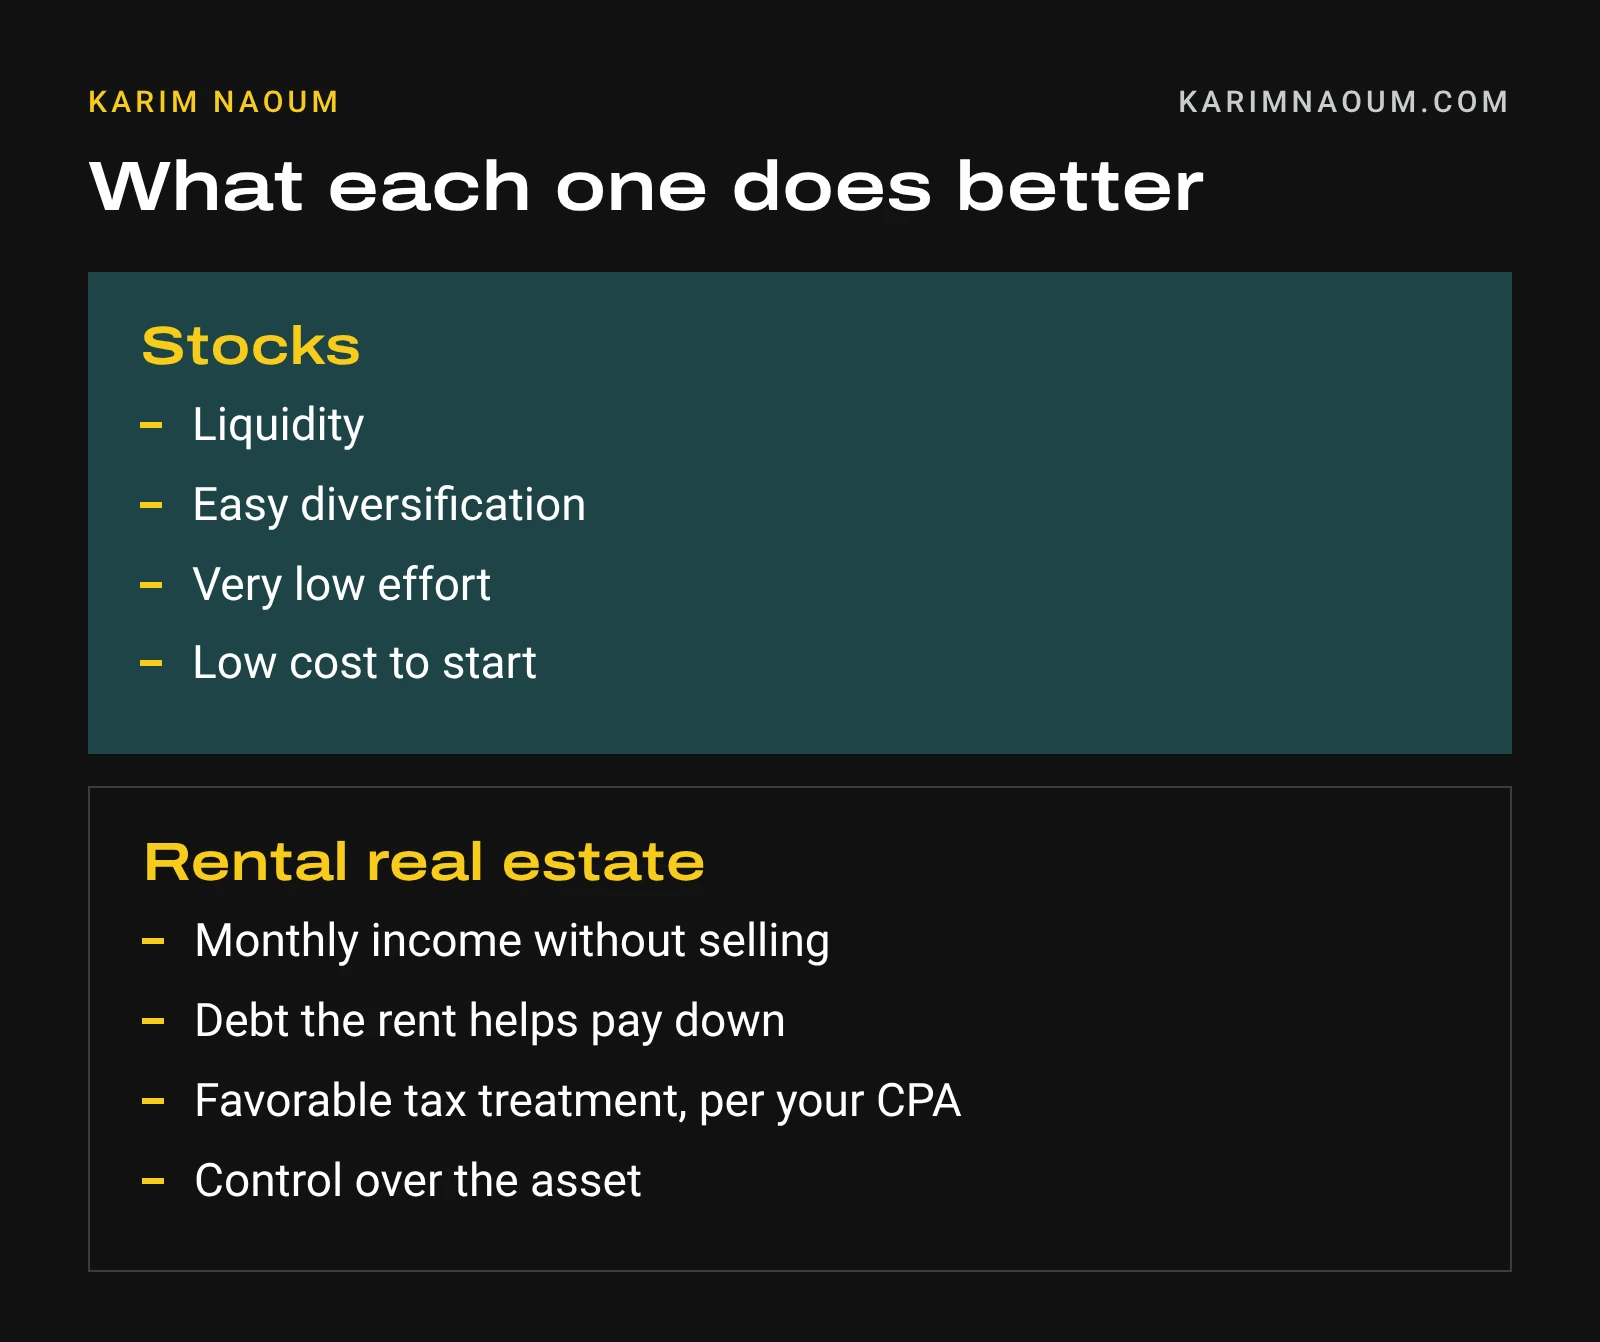
Liquidity. You can sell an index fund in seconds and have cash in days. Selling a rental takes months and often costs a meaningful share of the sale price in commissions and closing costs.

Diversification. One broad index fund spreads your money across hundreds of companies. By contrast, one rental property is a single asset in a single neighborhood. A bad tenant or a local economic downturn can hit hard.

Low effort. Automatic contributions to a retirement account take minutes a year. Meanwhile, even a well-managed rental takes ongoing attention.

Low cost to start. You can start investing in stocks with a few dollars. Rentals require a down payment, closing costs, and reserves.

Comparable long-run returns without the landlord work. There’s also the option of owning real estate through the stock market. NerdWallet, citing Morningstar data, reports that REITs, publicly traded real estate companies, returned an average of 11.8% per year from 1972 to 2019, versus 10.6% for the S&P 500. Past returns don’t predict future ones, but it’s a reminder that you don’t have to be a landlord to own real estate.

If someone tells you rental real estate beats stocks in every way, they’re selling something.

Strengths of stocks and strengths of rental real estate, with who each approach fits best

What rentals do that stocks can’t

Not every point in real estate vs stocks goes to the market. Rental real estate’s advantages come from its structure rather than from higher average returns.

  • Monthly income you don’t have to sell anything to get.
  • Debt that someone else helps pay down through rent.
  • Tax treatment that can be favorable, including depreciation deductions that often reduce taxable rental income. A CPA should advise on your situation.
  • Control over the asset and how it performs.
  • A physical asset that meets a basic need. People need housing in good markets and bad.

For investors who want to build income that grows over time and who don’t mind running a small business, those features can matter more than a fund’s liquidity. Karim’s broader rules for evaluating deals and managing risk are collected in Karim Naoum’s investing principles.

Real estate vs stocks: why many investors do both

The real estate vs stocks debate often assumes you have to choose. Most people don’t.

Plenty of investors keep retirement savings in index funds through a workplace plan and build a rental portfolio with separate capital. The stocks provide diversification, liquidity, and low-effort growth. The rentals provide monthly income and a business they control. Together, each covers the other’s weaknesses.

A few reasonable ways people split it:

  • Keep retirement accounts in index funds and use taxable savings for rental down payments.
  • Build an emergency fund and rental reserves first, so a vacancy never forces you to sell stocks at a bad time.
  • Use rentals for income and stocks for growth, and rebalance as your goals change.

What matters is that each investment has a job, and that you’re not putting money into rentals you’ll need back on short notice.

Who each fits

There is no universal winner in real estate vs stocks, only a better fit for each person. Stocks and index funds tend to fit people who:

  • Want low effort and broad diversification
  • Need to be able to access their money quickly
  • Are starting with small amounts
  • Don’t want to deal with tenants, repairs, or housing agencies, even indirectly

Rental real estate tends to fit people who:

  • Want monthly income, not just long-term growth
  • Are comfortable using mortgage debt responsibly
  • Have capital for a down payment and reserves
  • Are willing to build a team and oversee a business
  • Can hold properties for the long term

Section 8 rentals are a specific slice of that second group. They suit investors who want the stability of a government-backed rent payment and are willing to learn the inspection and paperwork process that comes with it. They aren’t for everyone, and any honest program should say so. For a side-by-side look at how voucher rentals compare with traditional market-rate rentals, see Section 8 vs traditional rentals.

The bottom line on real estate vs stocks

Overall, stocks are easier, more liquid, and easier to diversify. Rental real estate offers monthly income, the power of long-term mortgage debt, and control over your results, at the cost of effort, concentration, and risk if you buy badly or skip reserves.

Karim’s work centers on Section 8 rentals because his approach prioritizes steady cash flow from a basic need, financed carefully and held for the long term. That case is strongest for people who want income, have capital, and are willing to learn the system. It’s weakest for people who want something truly passive or need their money available on short notice.

Explore more of Karim’s thinking

Real estate vs stocks is only one part of how Karim thinks about investing. If you want to understand the reasoning behind Karim’s strategy in more depth, start with his investing principles and his view on risk in real estate. For the story of how he got here, read the full Karim Naoum biography. And if you’re ready to explore Section 8 investing as a path for yourself, the program he founded, Section 8 Training, explains how it works.

Karim Naoum on Building a Personal Brand as a Real Estate Investor

Karim Naoum has built one of the larger audiences on social media in the Section 8 niche. Most real estate investors are invisible online, and that’s usually fine. You don’t need an audience to buy a rental. But for investors who want partners, deal flow, lenders who take their calls, or a business beyond their own portfolio, a personal brand can open doors that cold outreach can’t.

Karim Naoum is one of the more visible examples in the Section 8 niche. As Section 8 Karim, he built a following around a narrow topic, rental properties leased to families with Housing Choice Vouchers, and turned that attention into an education company, Section 8 Training. Karim Naoum’s social media presence is a big part of how many people first hear about Section 8 investing at all.

This article looks at what the Section 8 Karim brand shows about building credibility online as an investor: why a narrow focus works, what kind of content earns trust, the mistakes that come with visibility, and practical advice for investors who want to start posting without turning into a hype account.

Why a niche brand works

The clearest lesson from Karim Naoum on social media is focus. The most obvious thing about the Section 8 Karim brand is the name. It isn’t “Karim Real Estate” or “Karim Investing.” It names one strategy.

That narrow focus does a lot of work:

  • It’s memorable. People remember “the Section 8 guy” far more easily than “a real estate investor.”
  • It attracts the right audience. Someone who follows a Section 8 account is already interested in voucher rentals, not flipping, wholesaling, or short-term rentals.
  • It builds depth. Talking about one subject for years forces you to know it well. Inspections, payment standards, housing agency paperwork, and tenant relationships become content because they’re what the audience actually asks about.
  • It fits real experience. Karim worked at a local Housing Authority at 17, which gave him an inside view of the voucher program before he owned rentals. A brand built on that experience has something to say that general real estate content doesn’t.

For new investors, the lesson isn’t to copy the Section 8 angle. It’s to pick a lane narrow enough that people know exactly what you’re about, and real enough that you can talk about it for years without running out of things to say.

Karim Naoum on social media: what earns trust

Attention is easy to get with big numbers and expensive cars. Trust is harder. The investors who keep an audience over time tend to post a few kinds of content consistently.

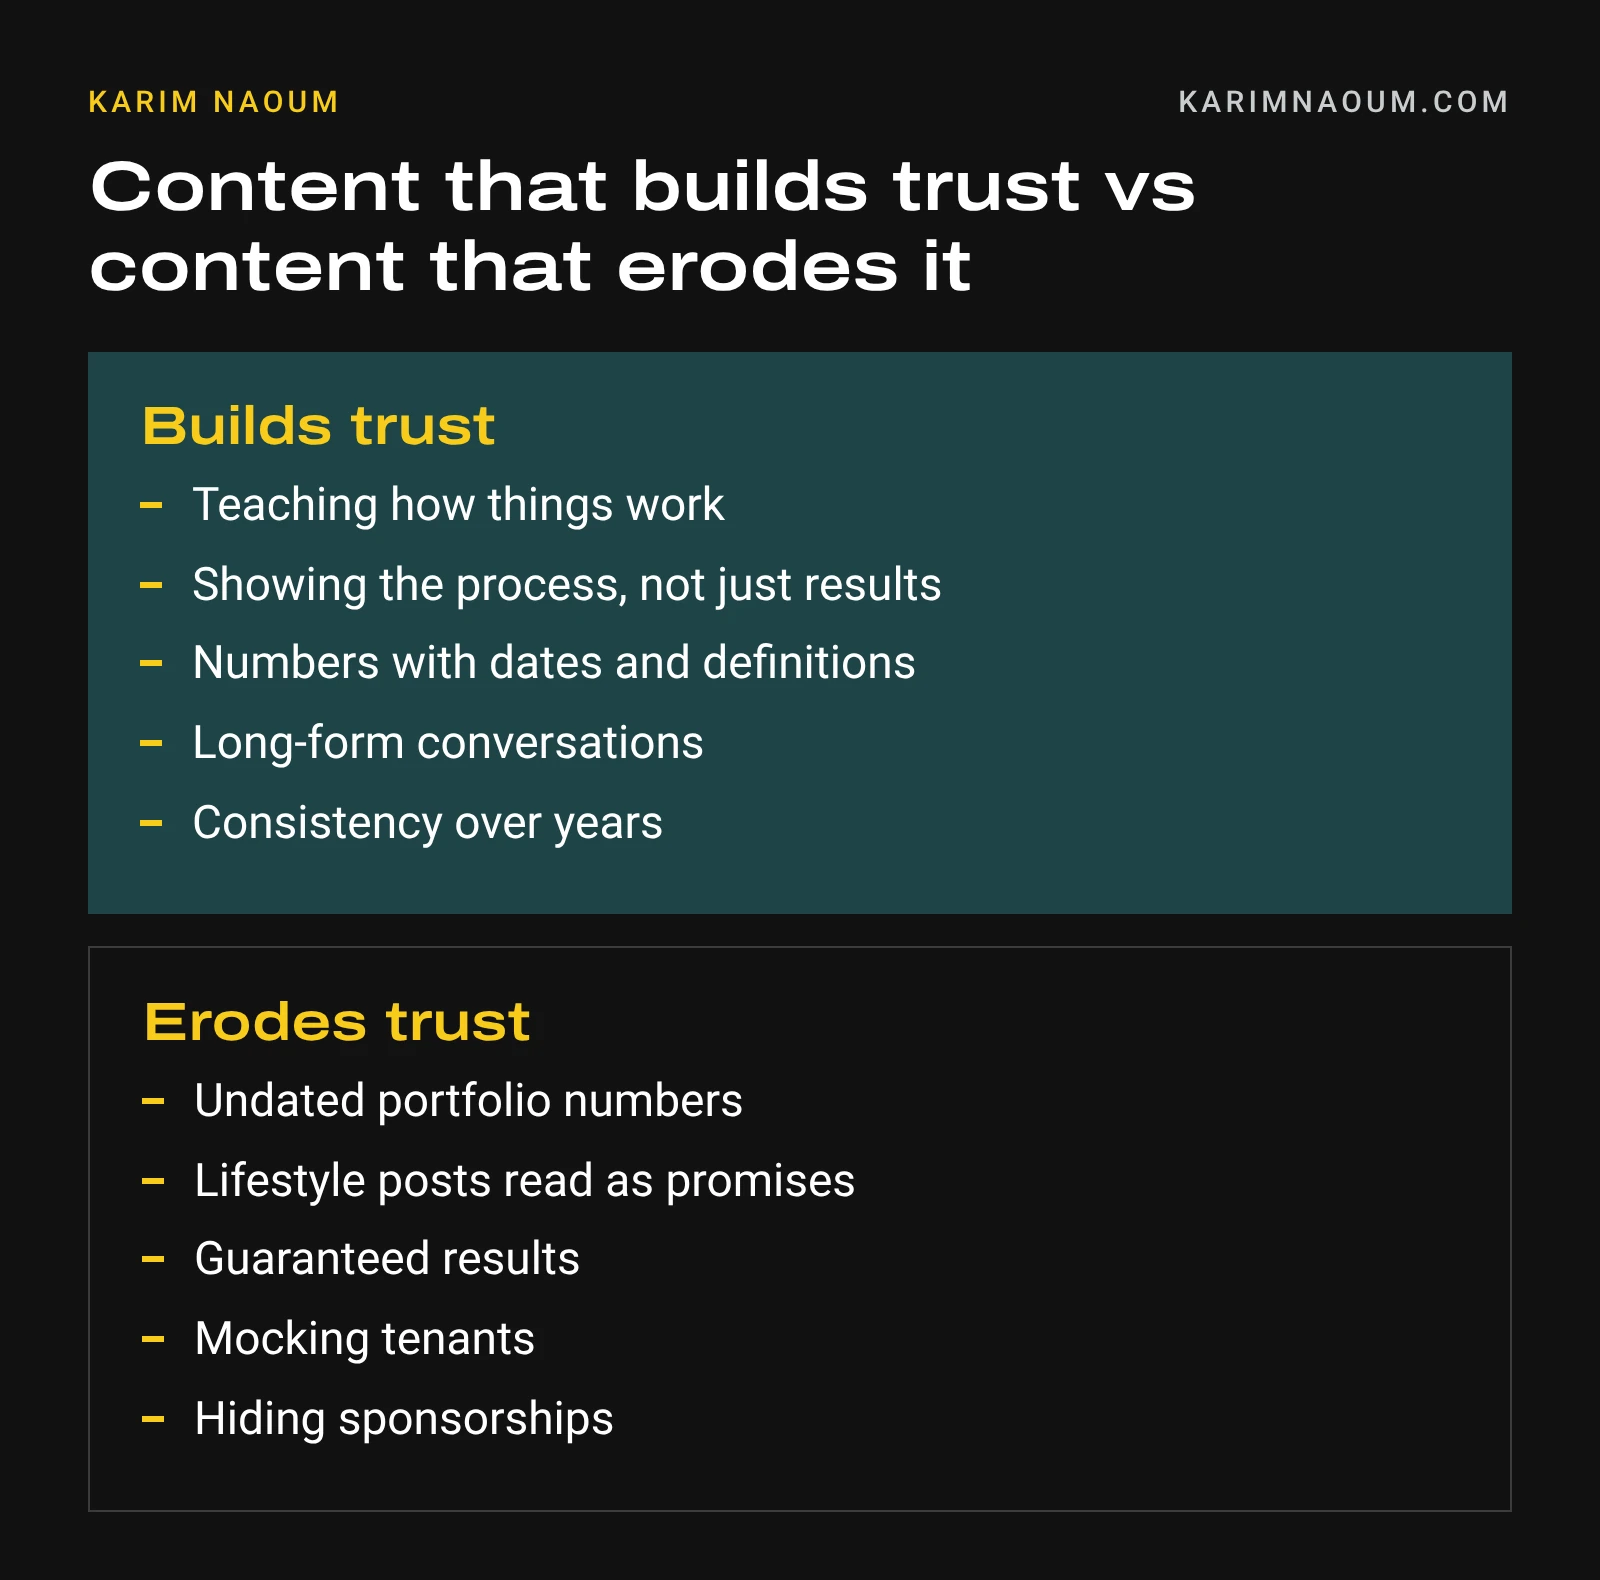
Content that builds trust for real estate investors on social media versus content that erodes it

Teaching. Explaining how something works, such as how a housing agency approves rent or what inspectors check, gives people value whether or not they ever buy anything. Teaching content is also what people save and share.

Process over results. Showing how a deal was analyzed, what went wrong in a renovation, or how a failed inspection got fixed is more believable than showing a closing photo.

Specifics with context. Numbers are useful when they come with dates and definitions. “150 rentals” means little without when it was said and what was counted. Karim’s approved figure is 400+ properties as of 2026, counting wholly owned properties and partnership interests, and the reason that wording exists is that undefined numbers get repeated, mixed up, and challenged. His views on why clear claims matter are laid out in Karim Naoum on transparency in real estate education.

Long-form conversations. Podcast interviews let people hear how an investor actually thinks, beyond a 30-second clip. Karim has appeared on shows including Dropping Bombs with Brad Lea, episode 798, released March 17, 2025. A collection of others is on his media coverage page.

Consistency. Showing up on the same topics, in the same voice, for years. Most of the trust in any brand comes from repetition.

If you want to see how Section 8 Karim content is organized by topic, this guide to Section 8 Karim videos and what to watch first sorts it for newcomers.

Mistakes and lessons that come with visibility

Visibility on social media has a cost, and Karim Naoum has run into most of it. Visibility has costs, and anyone building a brand in real estate education runs into them. The Section 8 Karim brand has dealt with several that are worth learning from.

Numbers that outrun their context. When figures are shared at different times and counted different ways, older numbers keep circulating. Profiles and articles about Karim have cited different property counts over the years. The fix has been a single source of truth: an official FAQ that answers the questions people ask about him. Any investor who shares portfolio numbers publicly should date and define them from day one.

Impersonators. A large following attracts fake accounts that copy names and photos to run scams. That’s why the brand maintains an official list of Section 8 Karim websites and accounts and tells followers that the team will never DM them first asking for money.

Critics. Visible people get criticized, sometimes fairly and sometimes not. Ignoring every criticism looks evasive. Arguing with every comment is exhausting. Karim’s approach has been to answer the substantive criticisms directly, which he does in Karim Naoum answers his critics.

Lifestyle content read as a balance sheet. Posts about purchases or travel can be read as claims about wealth or as promises about what followers will earn. They’re neither, but they’re often taken that way. That’s one reason the brand doesn’t publish a net worth figure.

The pull toward hype. Short-form video rewards bold claims. Real estate results depend on markets, financing, properties, and execution, and anyone promising fast or guaranteed results is overselling.

Teaching vs showing off

The best Karim Naoum social media content teaches rather than shows off. The line between teaching and showing off is where most investor brands succeed or fail.

Showing off sounds like: look what I bought, look how much I make, you could have this too. It gets attention, but it attracts people who want shortcuts, invites skepticism, and can cross into misleading marketing.

Teaching sounds like: here’s how this works, here’s what it costs, here’s what can go wrong, here’s how to check it yourself. It grows more slowly, but it attracts people who want to learn and builds credibility that lasts.

The practical test is simple. After someone watches your post, do they know something useful they didn’t before? If the only takeaway is that you have money, it’s showing off. Karim’s wider views on selling education honestly are in Karim Naoum on honest marketing.

If you mention a paid program, product, or sponsor, disclose that relationship clearly. The FTC’s Disclosures 101 for Social Media Influencers explains what’s expected, and it applies to real estate educators as much as anyone.

Advice for investors on social media, drawn from Karim Naoum

If you’re an investor thinking about building a presence, a few principles go a long way.

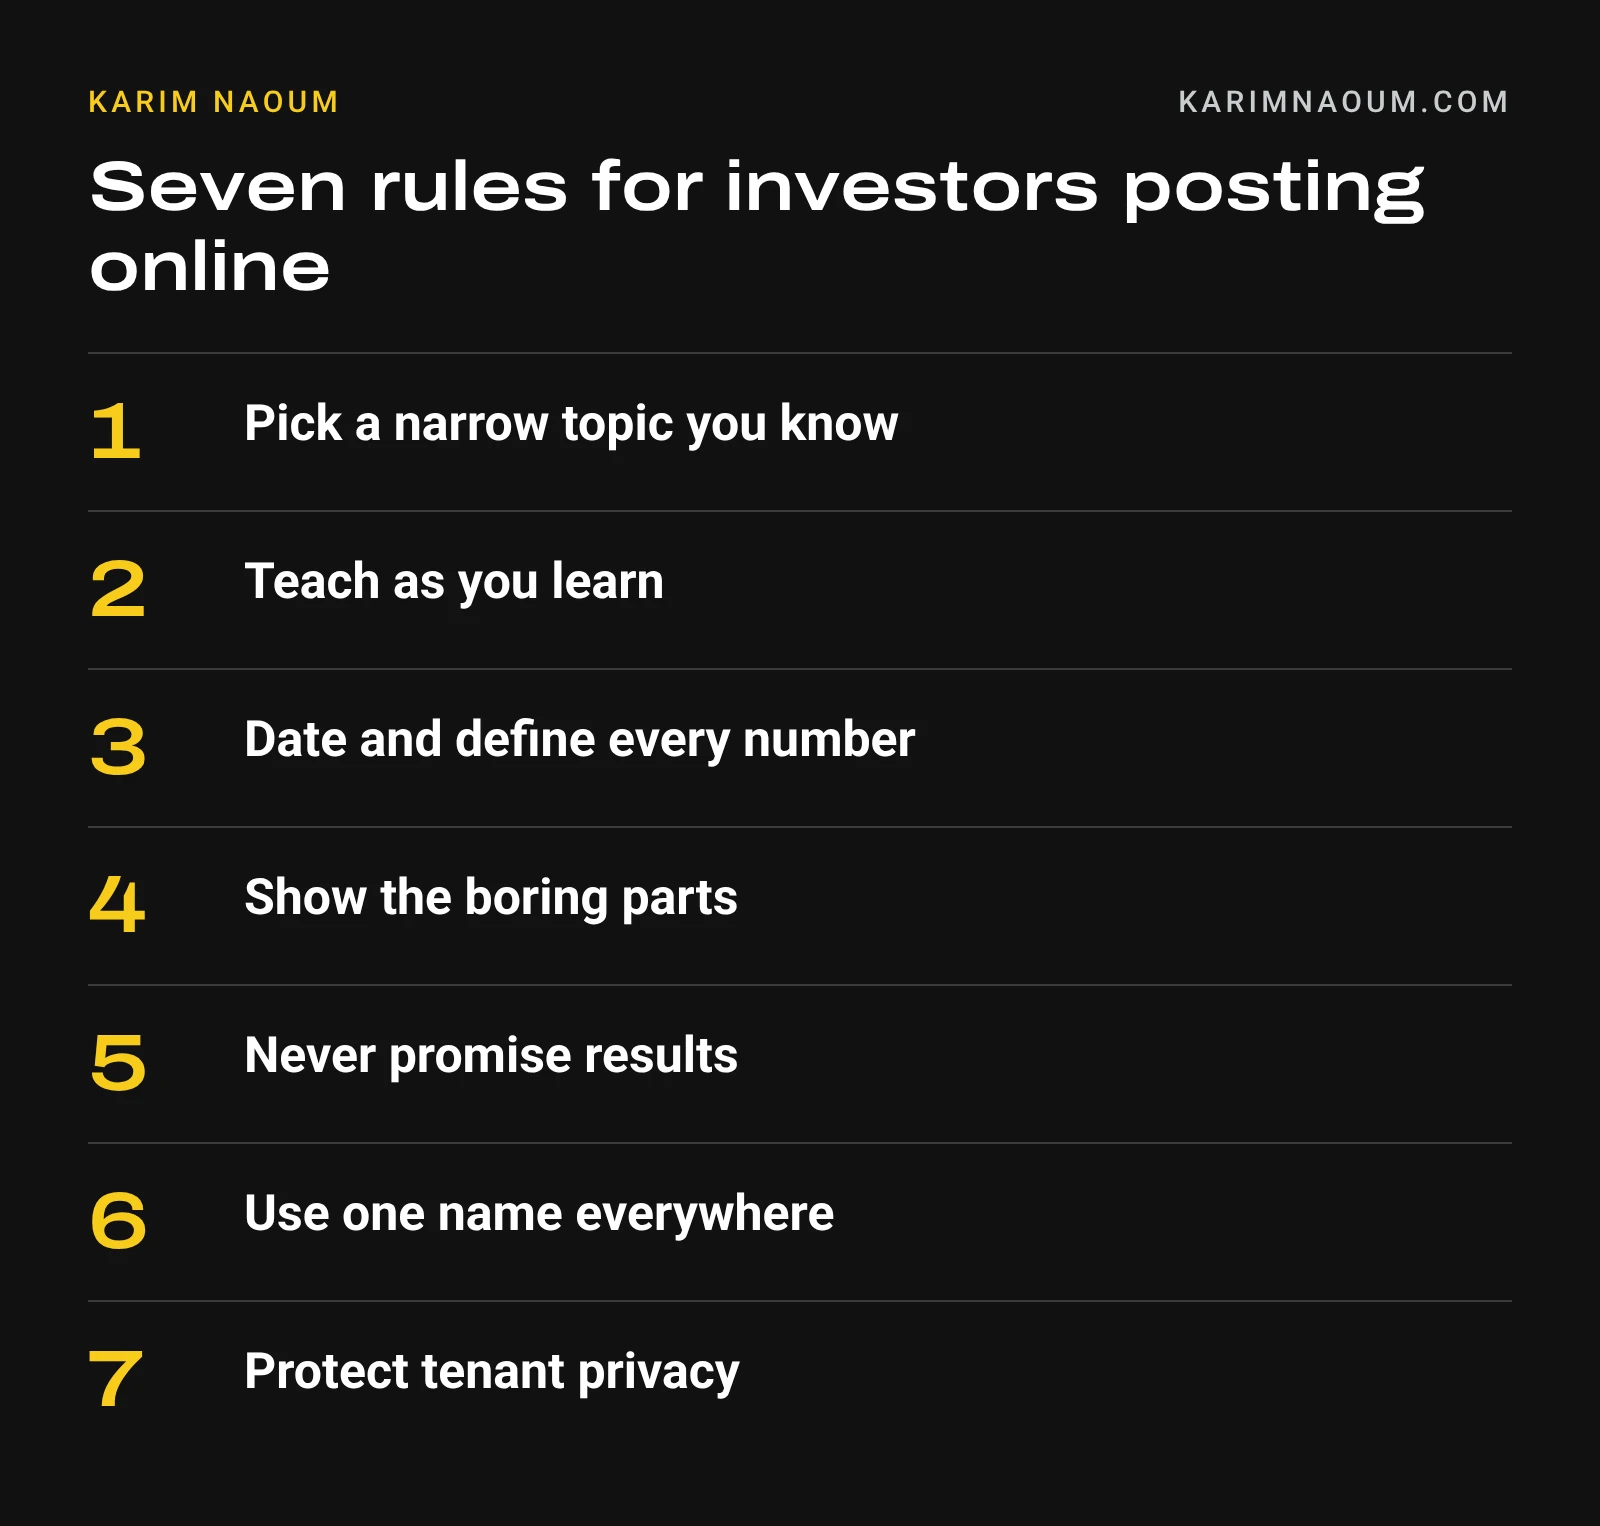
Seven tips for real estate investors building a personal brand online, from picking a niche to dating your numbers
  1. Pick a narrow topic you actually know. A market, a strategy, or a type of property. Depth beats breadth.
  2. Teach what you learn as you learn it. You don’t need to be an expert to share your process. Be honest about where you are.
  3. Date and define every number. “3 rentals as of March 2026, all owned with mortgages” is more credible than “growing portfolio.”
  4. Show the boring parts. Inspections, repairs, spreadsheets, and paperwork are what real investing looks like, and they’re what people searching for help actually want to see.
  5. Never promise results. Don’t imply followers will earn what you earn. Share what happened to you, with context.
  6. Use the same name everywhere and list your official accounts in one place. It helps followers and makes impersonators easier to spot.
  7. Protect your tenants’ privacy. Don’t post tenants’ faces, names, homes in identifiable detail, or their personal situations without clear permission.

That last point matters especially in the Section 8 niche. Voucher households are families, often including children, seniors, or people with disabilities. Their homes and circumstances aren’t content.

What not to post

Some content works against investors on social media, no matter how many views it gets, and the Karim Naoum brand avoids it. Some content creates problems even when it gets views:

  • Specific addresses of occupied rentals
  • Screenshots of tenant messages, ledgers, or paperwork with personal details
  • Claims about guaranteed rent, guaranteed deals, or guaranteed returns
  • Undated portfolio or income numbers
  • Mocking or stereotyping tenants
  • Anything that suggests followers can skip due diligence

Do you need a big following to benefit?

No. For most investors, a modest, focused presence does the job. A few dozen useful posts about one market or strategy can be enough to make lenders, agents, partners, and sellers take you seriously when they look you up. Audience size matters less than whether what they find is accurate and consistent.

Where the Karim Naoum brand goes next on social media

The Section 8 Karim brand spans four websites with distinct jobs: karimnaoum.com for Karim’s personal work and commentary, section8training.com for the training program, section8karim.com as the official brand hub, and masteringsection8.com for free landlord education. Splitting content that way keeps each site focused, which is the same niche principle applied across the whole brand.

The direction is toward more teaching and more transparency: dated facts, clear explanations of how the program works, and honest answers to hard questions. For a brand built in a niche that gets its share of criticism, that’s the path that lasts.

Explore more of Karim’s work

There is more to Karim Naoum than social media. To understand the story behind the brand, start with the full Karim Naoum biography, then browse his best interviews on Section 8 investing. For the lessons that shaped how he invests, read lessons Karim Naoum learned the hard way in real estate.